

October 23, 2026 | TickerRoast Markets Analysis
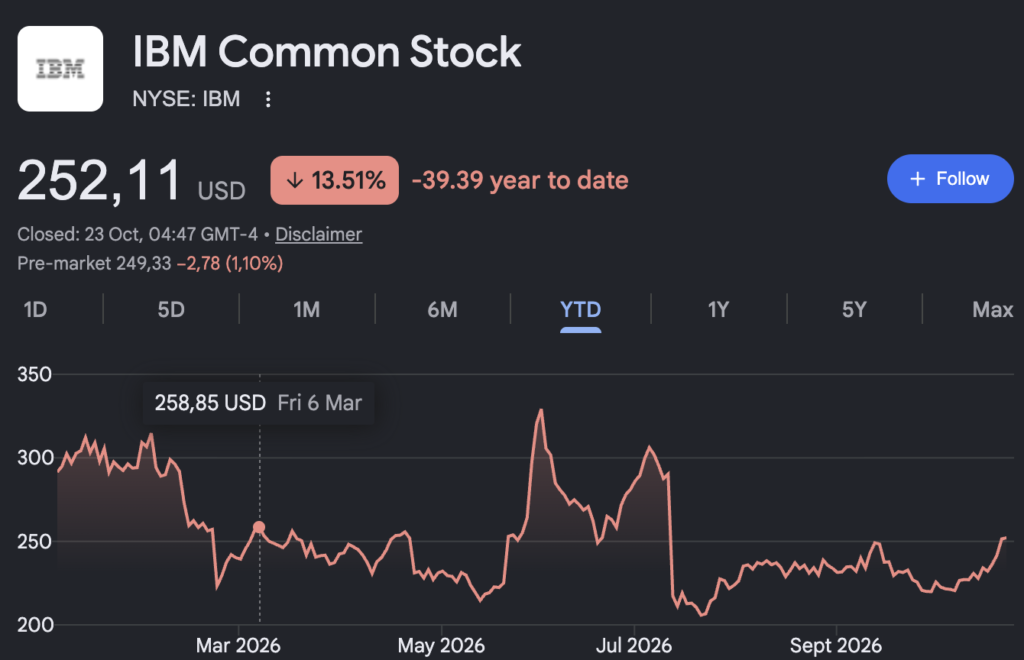
International Business Machines (NYSE: IBM) beat consensus on revenue and earnings for the third quarter of 2026, kept its full-year revenue outlook and raised its free-cash-flow outlook slightly. The shares still fell almost 5% in premarket trading on October 22, according to media reports, before ending the regular session at $252.11, up 0.26%, on about twice their usual volume. In our view, the swing shows how high the bar now is for AI-exposed technology companies: a clean beat was not enough to move the stock.
What happened
IBM reported third-quarter 2026 results after the close on October 21, 2026. According to CNBC, both revenue and earnings came in ahead of LSEG consensus. Adjusted earnings per share were $2.95. CNBC also reported that CEO Arvind Krishna pointed to customer traction for the company’s AI offerings. GuruFocus reported that revenue grew 6% at constant currency.
Management kept its calendar-2026 revenue outlook unchanged and raised its free-cash-flow outlook modestly, according to Investing.com. The same report said UBS raised its price target on IBM to $243 after the release and called the results mixed. That target is below the stock’s October 22 close of $252.11.
Benzinga and GuruFocus reported that IBM shares fell nearly 5% in premarket trading on October 22. That move erased the roughly 4% gain from the October 21 session, before the report came out. Yahoo Finance data compiled by our system show that the shares recovered during regular trading and closed 0.26% higher. Volume was 11.6 million shares, 2.11 times the 20-day average of about 5.5 million.
| Metric | Value | Source / date |
|---|---|---|
| Q3 2026 adjusted EPS | $2.95 (beat LSEG consensus) | CNBC, Oct 21, 2026 |
| Revenue growth, constant currency | +6% | GuruFocus |
| 2026 revenue outlook | Reiterated | Investing.com |
| 2026 free-cash-flow outlook | Modestly raised | Investing.com |
| UBS price target | Raised to $243 | Investing.com |
| Close, Oct 22, 2026 | $252.11 (+0.26%) | Yahoo Finance |
| Volume vs. 20-day average | 2.11x | Yahoo Finance |
| 52-week range | $199.19 – $332.46 | Yahoo Finance |
Why the stock moved
The sources point to three reasons a beat could still produce a sell-off before the open. In our view, the first is positioning. The shares had gained about 4% on results day and 8.31% over the month before the report, so some of the good news was likely already in the price. The second is guidance. IBM reiterated its revenue outlook rather than raising it. For a company whose valuation increasingly depends on software and AI growth, an unchanged top-line outlook can look to some investors like a lack of acceleration, even with a higher cash-flow outlook. The third is the market backdrop. The story notes a broad tech sell-off, and in that kind of market investors tend to reward only clear upside surprises in AI-related growth.
The regular-session recovery to a small gain suggests that buyers stepped in on the dip. The heavy volume shows that investors disagreed about how to read the quarter. Based on the sources available to us, we cannot say which investor groups were on each side.
Business and financial analysis
The investment case for IBM has rested more and more on three things: recurring software revenue (including Red Hat and automation), AI-related consulting and platform work, and its long-standing infrastructure business. Constant-currency revenue growth of 6% is solid for a company of IBM’s size and maturity, according to GuruFocus’s figures. The higher free-cash-flow outlook supports dividend capacity and the balance sheet. In our view, though, what will matter most from here is the mix of growth. Investors tend to give the most credit to software growth because it carries higher margins and more recurring revenue.
UBS raised its target to $243 while describing the results as mixed, as reported by Investing.com. That combination shows the split: the firm saw enough to lift its estimate of value, but the target sits below the current share price. This could suggest that at least some sell-side analysts see the stock’s valuation as fairly full after the recent rally. We have not reviewed UBS’s full note, and other firms may hold different views.
For context, IBM shares were down 11.54% over the past year as of October 22, 2026, while the S&P 500 rose 13.73% over the same period. Year to date, the stock was down 13.51%. Over three months, however, it had recovered 17.7%. The October 22 close was about 24% below the 52-week high of $332.46 and about 27% above the 52-week low of $199.19.
Technical picture
According to Yahoo Finance data as of October 22, 2026, IBM closed above all three of its main simple moving averages: the 20-day ($229.26), the 50-day ($232.71) and the 200-day ($250.67). The close above the 200-day average is narrow, less than 1%. The 20-day average is below the 50-day, which shows how quickly the latest leg of the rally has unfolded.
The 14-day relative strength index was 70.26, at the edge of the range many technicians treat as overbought. Volume at twice the 20-day average shows strong interest around the results. Technical indicators describe past price behaviour only and do not reliably predict future moves.
Key risks
- Growth mix: If software and AI revenue do not accelerate, a reiterated top-line outlook may keep weighing on how investors value the stock.
- Sector sentiment: A wider tech sell-off can pull AI-exposed names down regardless of their own results.
- Valuation and positioning: After a 17.7% three-month gain and an RSI near 70, the shares may react sharply to small disappointments.
- Consulting demand: Enterprise spending on discretionary IT services is sensitive to the economy.
- Currency: Reported growth can differ from constant-currency growth when exchange rates move.
What investors will watch next
In our view, the main items to monitor are:
- Whether IBM’s full 10-Q filing and later management commentary give more detail on software growth and AI bookings.
- Further analyst changes to ratings and targets after the UBS move reported by Investing.com.
- Whether the shares stay above the 200-day moving average, now around $250.67, after the high-volume session.
- Results from enterprise software and IT services peers, which will show whether IBM’s numbers reflect a company-specific pattern or a sector-wide one.
- Fourth-quarter seasonality, which has historically been important for IBM’s software and cash flow. Company outlooks are forecasts and are inherently uncertain.
Conclusion
On the reported figures, IBM’s third quarter of 2026 was a beat: adjusted EPS of $2.95 topped LSEG consensus, constant-currency revenue grew 6%, and the free-cash-flow outlook went up. The near-5% premarket drop and the later recovery to a flat close show a market weighing solid execution against a full valuation, an unchanged revenue outlook and a difficult backdrop for technology stocks. In our view, the next stage of the stock’s performance is likely to depend less on headline beats and more on evidence that software and AI growth can accelerate. That outcome remains uncertain.
Sources
- IBM beats on top and bottom lines as CEO Krishna touts ‘Super Intelligence’ traction — CNBC
- IBM Shares Are Falling Thursday: What’s Happening? — Benzinga
- UBS raises IBM stock price target to $243 on mixed Q3 results — Investing.com
- IBM Shares Drop Nearly 5% Pre-Market Despite Solid Q3 Earnings — GuruFocus
Market data: Yahoo Finance, close of 2026-10-22.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 23, 2026 and market data as of the 2026-10-22 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Related reading
- RingCentral Stock Jumps 15% After Hours as AI Products Help Lift Guidance
- Oracle’s Year-Long Stock Slide Has Erased About $200 Billion From Larry Ellison’s Fortune
- American Express Stock Falls Despite Record Revenue as It Plans to Cut About 5% of Jobs
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

