

October 28, 2026 | TickerRoast Markets Analysis
Enphase Energy’s third quarter landed at the bottom of its own range, and its fourth-quarter outlook points lower still. The microinverter maker is trying to sell investors on a future in AI data center power, but the stock’s drop on Wednesday shows the market is still pricing the residential solar business it has today.
Sell-Through Barely Moved
According to the results Enphase filed with the SEC on October 27, revenue for the third quarter was $293.3 million, against $291.9 million in the second quarter and $410.4 million a year earlier. That is a decline of roughly 29% year over year. The figure included $85.0 million of what the company calls safe harbor revenue, which compares with $84.3 million in the second quarter.
The more telling number was sell-through, meaning the products installers actually pulled from distributors. Enphase says global sell-through rose only about 1% from the second quarter, against its own expectation of 10% growth, and that this left revenue at the low end of guidance. In the United States, sell-through rose 5% sequentially but fell 35% from a year earlier, which the company says is broadly in line with third-party data on the residential solar market. In Europe it fell 12% sequentially, with France singled out as soft.
| Metric (non-GAAP unless noted) | Q3 2026 | Q2 2026 | Q3 2025 |
|---|---|---|---|
| Revenue | $293.3M | $291.9M | $410.4M |
| Gross margin | 45.0% | 46.8% | 49.2% |
| Operating income | $53.6M | $56.7M | $123.4M |
| Diluted EPS | $0.41 | $0.46 | $0.90 |
| GAAP diluted EPS | $0.17 | $0.27 | $0.50 |
Margins Slip and Cash Generation Stalls
Non-GAAP gross margin fell to 45.0% from 46.8% in the second quarter, which the company blames on product mix. Reciprocal tariffs cost about 1.3 percentage points of margin, less than the roughly 2.0 points of the previous quarter. Non-GAAP operating income slipped to $53.6 million and non-GAAP diluted EPS to $0.41. On a GAAP basis, operating income was just $6.5 million and diluted EPS $0.17, and the company notes that impairments on investments cut GAAP and non-GAAP EPS by $0.15 and $0.14 respectively.
The cash line stood out to me. Enphase generated approximately $0.1 million of operating cash flow in the quarter, essentially zero, while spending $11.5 million on capital expenditures. It still ended September with $931.8 million in cash, cash equivalents and marketable securities, so liquidity is not the issue. The issue is that a company once known for converting a large share of revenue into cash had a quarter in which it converted almost none.
A Fourth-Quarter Outlook That Points Lower
The guidance is what moved the stock. Enphase expects fourth-quarter revenue of $225.0 million to $255.0 million, including 100 to 120 MWh of IQ Battery shipments and about $51.2 million of safe harbor revenue. The midpoint, $240 million, would be about 18% below the third quarter. Management assumes sell-through will fall another 10% from the third quarter. Non-GAAP gross margin is guided to 40.0% to 43.0%, including about 2.0 points of tariff impact, below the 45.0% just reported.
The company is candid about why. It says its core U.S. residential solar market faces headwinds from higher interest rates and the expiration of the Section 25D federal tax credit for homeowners. With the Federal Reserve holding its policy rate at 3.75% to 4% on Wednesday and long-term yields elevated, the financing side of that problem is not going away soon.
The Market Delivers Its Verdict
According to 24/7 Wall St., the stock was down 17% before the open, and SolarEdge fell about 6% in sympathy. StockTitan’s live coverage showed Enphase down 15.9% at 10:02 a.m. Eastern and 17.1% at 3:01 p.m., so there was little attempt at a rebound during the session. The stock closed at $24.99, down 16.0% from $29.76, according to Yahoo Finance data.
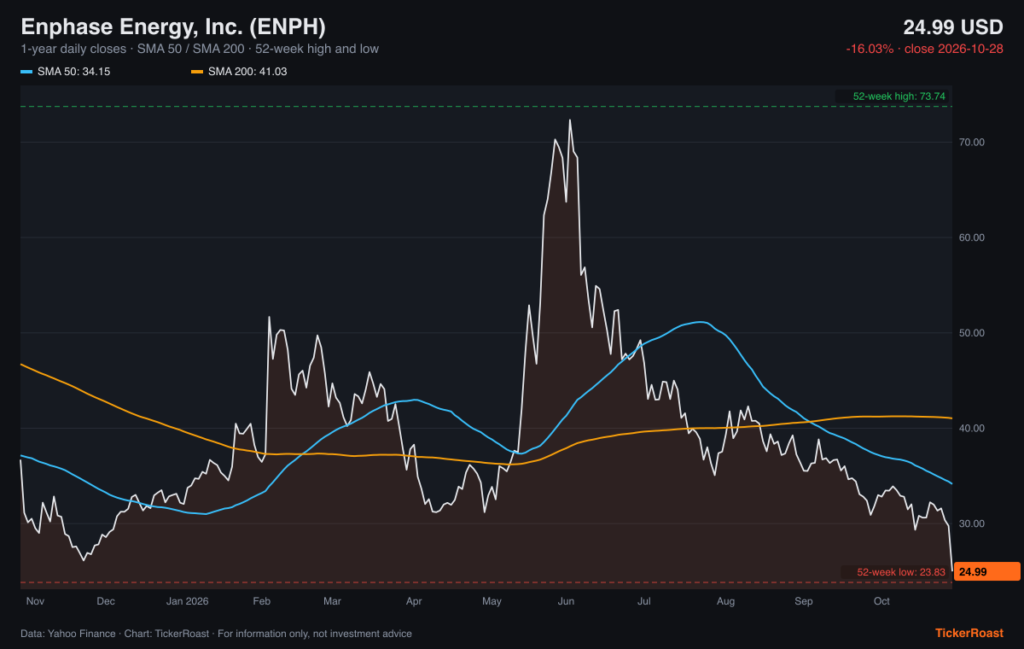
The one-year chart frames the problem. The shares spiked above $70 in June, then slid for four months, and Wednesday’s drop leaves them in the mid-$20s, a whisker above the 52-week low, at roughly a third of the 52-week high and well below both the 50-day and 200-day moving averages. The 50-day line has been falling since August, which tells me this is a trend rather than a single bad quarter.
The Data Center Pivot Is Real, but Years Away
Enphase spent a large part of its release on the IQ SST, a solid-state transformer designed to convert medium-voltage AC power directly to 800 volts DC for AI computing racks. The company says it demonstrated 13.8 kV AC to 800 VDC conversion at its Austin lab using 132 power modules, that it more than doubled its IQ SST customer and partner pipeline to over 50 during the quarter, and that it is working with a leading hyperscaler and a global AI computing leader. It also announced it will use 900 V gallium nitride switches from Infineon in the power modules.
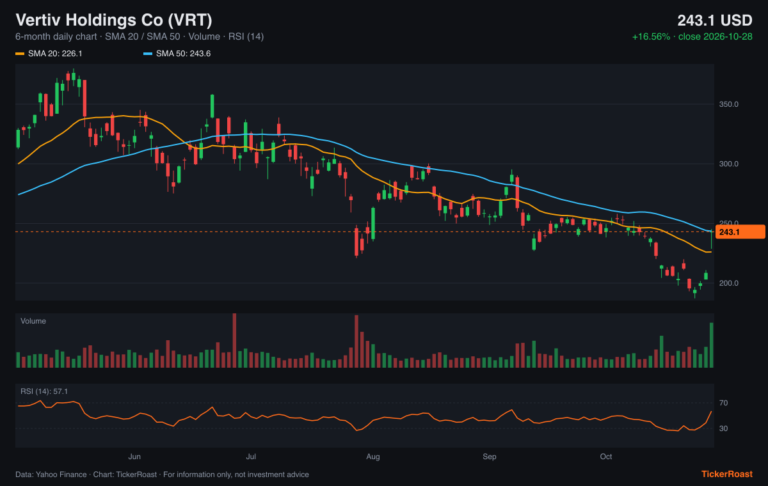
I think the technology is credible and the market is real, as Vertiv’s results on the same morning showed. The timeline is the problem. Enphase says customer pilots are planned for 2027 and commercial shipments are expected to begin in 2028. Until then, the income statement depends on residential solar, batteries, commercial microinverters and EV chargers. The company lists five growth drivers for 2027, including its fifth-generation IQ Battery, a prepaid lease program called Propel and the IQ Battery C80 for commercial customers.
There is also an awkward detail in the cash flow statement. Enphase made no share repurchases in the first nine months of 2026, compared with about $130 million in the same period of 2025, and it paid $632.5 million to settle notes that came due this year. With the core business shrinking and a long-dated product program to fund, that restraint looks like prudence. The next markers are the 34.5 kV validation and the megawatt-scale demonstration the company has promised by the end of 2026, and whether U.S. sell-through stabilizes once the tax credit comparison is out of the numbers.
Sources
- Enphase Energy third quarter 2026 financial results (Form 8-K, Exhibit 99.1) — SEC / Enphase Energy
- Vertiv Soars 16% and Enphase Sinks 17%: 6 Stocks Moving Before the Bell — 24/7 Wall St.
- Stock Market Today Live October 28, 2026 — StockTitan
- ENPH quote and chart — Yahoo Finance
Market data: Yahoo Finance, close of 2026-10-28. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 28, 2026 and market data as of the 2026-10-28 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

