
November 4, 2026 | TickerRoast Markets Analysis
Skyworks Solutions reported its last quarter as a standalone company and its first outlook as a combined group with Qorvo, and the market did not like the starting point. The December-quarter guidance came in below Wall Street estimates, weighed down by softness in Android phones, and the shares slumped about 16% after hours, according to CNBC.
A Combined Company Starts Below Consensus
According to Skyworks’ earnings release, filed with the SEC on November 3, the company expects revenue of $1.80 billion to $1.90 billion for its first fiscal quarter of 2027, the December quarter and the first since closing its combination with Qorvo in early October. At the midpoint, it expects non-GAAP diluted EPS of $1.25, based on about 241 million diluted shares and including about $50 million of other expense, mainly interest on the acquisition financing.
That fell short on both lines. According to CNBC, analysts polled by LSEG expected $1.50 a share and $1.99 billion in revenue. CNBC reported that Skyworks shares slumped about 16% in extended trading after closing Tuesday at $85.40, according to Yahoo Finance data.
Why the Guide Looks Weaker Than It Is, and Why It Still Disappoints
Skyworks laid out the bridge itself. Combined September-quarter revenue was about $1.98 billion, made up of $1,046 million from Skyworks and $937 million from Qorvo. But Qorvo’s quarter included an extra week worth about $70 million. CFO Philip Carter said the midpoint of the outlook is down about 7% sequentially from the combined figure, or about 3% excluding that extra week. At the midpoint, legacy Skyworks contributes about $1.07 billion and legacy Qorvo about $780 million.
The extra week explains part of the gap with consensus, but not all of it. Carter said smartphone revenue should decline by a low-teens percentage sequentially, citing seasonality, “well-known softness in the Android market” and the extra week. I read that as the core of the disappointment: the combined company still depends heavily on handsets, and the guide shows that this exposure did not get easier with the merger.
| Item | Figure | Source |
|---|---|---|
| Skyworks fiscal Q4 revenue (standalone) | $1,046M | Skyworks |
| Qorvo September-quarter revenue | $937M | Skyworks |
| Combined September-quarter revenue | about $1.98B | Skyworks |
| December-quarter revenue guide | $1.80B-$1.90B | Skyworks |
| December-quarter non-GAAP EPS guide (midpoint) | $1.25 | Skyworks |
| LSEG consensus | $1.50 EPS, $1.99B revenue | CNBC |
The Last Standalone Quarter
The reported quarter was Skyworks on its own. Fourth fiscal quarter revenue was $1,046 million, GAAP diluted EPS was $0.15 and non-GAAP diluted EPS was $1.28. For fiscal 2026 as a whole, revenue was $3.96 billion, with GAAP diluted EPS of $1.14 and non-GAAP diluted EPS of $5.05. The gap between GAAP and non-GAAP results reflects the costs around the Qorvo transaction, which will continue to blur reported earnings for several quarters.
Starting with the December quarter, Skyworks will report two revenue categories: Smartphone and Diversified Growth Markets. The second, which includes data center, defense, infrastructure and automotive, is expected to grow by a low single-digit percentage sequentially and by a high single to low double-digit percentage year over year on a combined basis, representing more than 40% of sales. The company also reported timing design wins in AI data center networking, including 1.6T switches, and said it has begun shipping clocks for leading AI hyperscalers’ rack-scale systems.
Synergies Are Back-Loaded
The merger case rests on cost savings, and they will take time. Skyworks reiterated a target of $500 million or more in annual cost synergies within 24 to 36 months of closing. For fiscal 2027, it expects about $150 million of operating expense synergies, weighted to the second half, and an annualized run rate of about $250 million to $300 million by the end of the year. The December-quarter outlook “reflects only the early stages of synergy realization,” Carter said.
There was some good news on the balance sheet. Skyworks said Moody’s upgraded it to investment grade at Baa3 after the combination closed, and Fitch revised its outlook to stable from negative while affirming a BBB+ rating. That should help with refinancing the acquisition debt, whose interest cost now shows up in the guidance.
The Chart Shows a Stock That Had Run Ahead
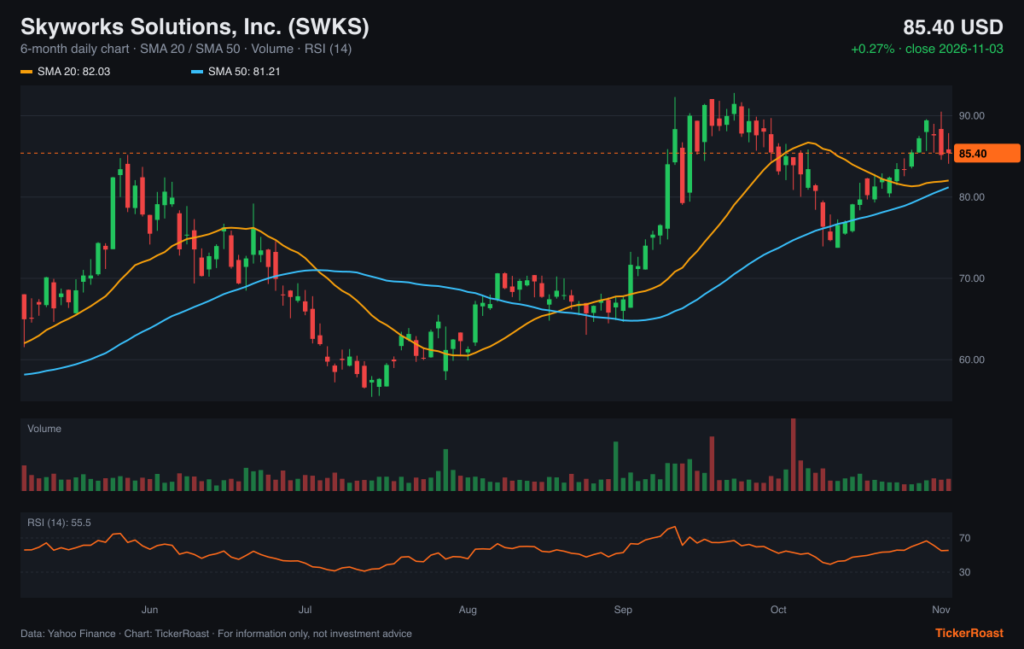
Before the report, the stock had performed well. According to Yahoo Finance data, Skyworks closed Tuesday at $85.40, near its 52-week high of $91.45 set on September 23 and above both its 20-day moving average near $82 and its 50-day average near $81, with a 14-day RSI around 55, after a rally from a six-month low of $56.58 in mid-July. A decline of about 16% would take the shares back below both averages and erase a large part of the gains made since the summer, which shows how much the market had priced in a smooth start for the combined company.
Qualcomm’s report after the close today will offer a direct read on Android demand, the same market Skyworks flagged as soft. If Qualcomm describes a similar trend, the problem looks cyclical and industry-wide; if not, the pressure on Skyworks may say more about its own customer mix as it starts life as a larger company.
Sources
- Skyworks Begins New Chapter Following Qorvo Combination; Reports Fourth Quarter and Fiscal 2026 Results (Form 8-K, Exhibit 99.1) — Skyworks Solutions via SEC EDGAR
- Stocks making the biggest moves after hours — CNBC
- Skyworks Solutions (SWKS) quote and history — Yahoo Finance
Market data: Yahoo Finance, close of 2026-11-03. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of November 4, 2026 and market data as of the 2026-11-03 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.