
November 4, 2026 | TickerRoast Markets Analysis
Arista Networks reported its fastest revenue growth since going public, a 58.5% jump to $3.66 billion, as spending on the networks that connect AI accelerators kept accelerating. The company beat its own guidance by more than $350 million and forecast up to $4 billion in fourth-quarter revenue. The shares rose about 9.5% in after-hours trading, recovering part of a slide of more than 20% from their October high.
Growth That Beat Arista’s Own Forecast by a Wide Margin
The figures come from the earnings release Arista filed with the SEC on November 3. Revenue for the quarter ended September 30 reached $3,657.6 million, up 58.5% from $2,308.3 million a year earlier and up 20.5% from the second quarter. Arista had guided to about $3.3 billion. Chief executive Jayshree Ullal called it “another momentous quarter with the highest year-over-year revenue growth since our IPO and record profitability.”
Profit grew even faster than sales. GAAP net income rose to $1.56 billion from $853.0 million, and GAAP diluted earnings per share reached $1.22, against $0.67 a year earlier. Non-GAAP diluted EPS was $1.20, up from $0.77. StockTitan’s earnings calendar listed a consensus estimate of $0.99 per share, which would make this a beat of more than 20% on the bottom line.
| Metric | Q3 2026 | Q3 2025 |
|---|---|---|
| Revenue | $3.66 billion | $2.31 billion |
| GAAP gross margin | 63.6% | 64.6% |
| Non-GAAP gross margin | 64.0% | 65.2% |
| GAAP operating margin | 44.9% | 42.4% |
| Non-GAAP operating margin | 49.1% | 48.6% |
| Non-GAAP diluted EPS | $1.20 | $0.77 |
Margins Show the Cost of Selling to Hyperscalers
The table shows the trade-off in Arista’s business. Gross margin slipped about one point year over year on both a GAAP and non-GAAP basis, which is consistent with a mix that leans more heavily toward the largest cloud and AI customers, who buy in volume and negotiate hard on price. Operating margin nonetheless improved, to 49.1% on a non-GAAP basis, because revenue grew far faster than operating expenses. For a hardware company, keeping almost half of every dollar of sales as operating profit is exceptional.
The balance sheet points in the same direction as the income statement. Current deferred revenue rose to $5.10 billion at the end of September from $4.00 billion at the end of 2025, and non-current deferred revenue increased to $1.74 billion from $1.37 billion, according to the release. Deferred revenue is product and service revenue Arista has billed but not yet recognized, often tied to customer acceptance of new deployments, so its growth is a reasonable sign that the pipeline remains full.
AI Networking Moves to the Rack
The product highlights in the release explain where the growth is coming from. Arista says it launched open rack-scale AI architectures with partners including AMD, Arm, Broadcom, Meta, Microsoft and Qualcomm, introduced an Etherlink system supporting up to 144 accelerators per rack in a single hop, and is pursuing a scale-across strategy built around its 7800 AI Spine. In plain terms, Arista is positioning Ethernet as the fabric that connects thousands of GPUs inside and between data centers, a market that grows directly with the AI buildout.
That link to the buildout cuts both ways today. The same demand that powered AMD’s record data center quarter powered Arista’s, and both reports landed on the evening Democrats won control of the Senate, a result investors fear could bring more limits on data centers, according to CNBC as relayed by StockTitan. Arista’s numbers describe orders already placed. The political debate is about what gets built in 2027 and 2028.
A Guide to as Much as $4 Billion
For the fourth quarter, Arista expects revenue of $3.9 billion to $4.0 billion, a non-GAAP operating margin of 48% to 49% and non-GAAP diluted EPS of $1.26 to $1.30, according to the release. The midpoint implies sequential growth of about 8%, a slower pace than the 20.5% jump just reported. Given that Arista beat its third-quarter forecast by more than 10%, I read the guidance as conservative rather than as a sign of slowing demand. The release does not include a 2027 outlook.
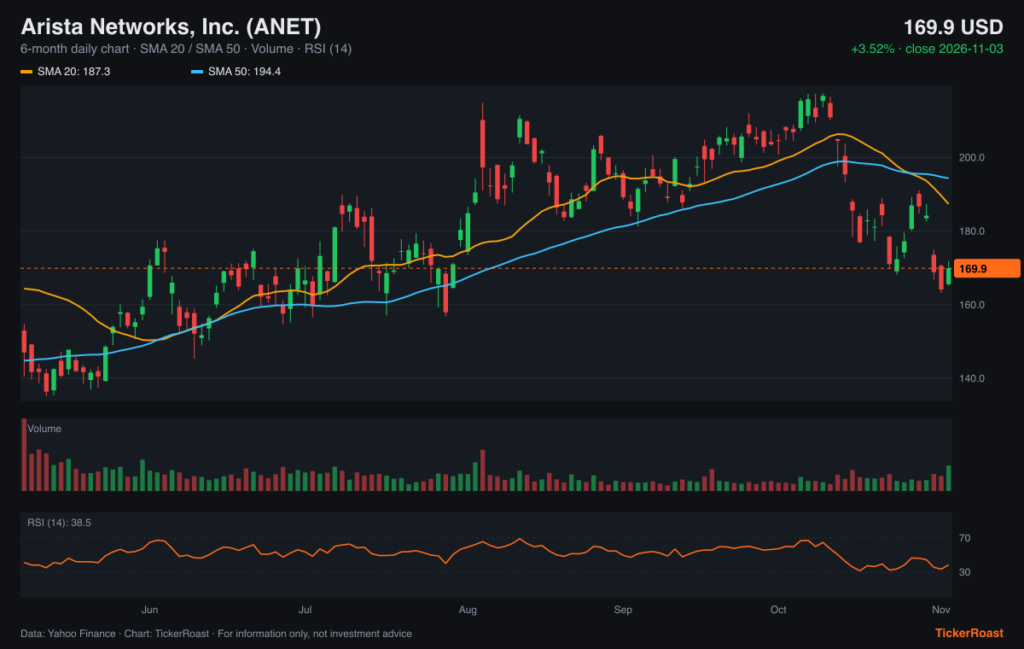
The chart shows Arista’s shares over the past six months with their moving averages, volume and RSI. The stock closed Tuesday at $169.91, about 22% below its October 9 high of $216.74 and below both its 20-day average near $187 and its 50-day average near $194, with a 14-day RSI around 35. The after-hours price of about $186, according to Yahoo Finance, would bring it back to the 20-day average. The 200-day average near $166 sat just below Tuesday’s close.
Valuation After the Correction
The October selloff did not spare Arista, even though nothing in this report suggests its business deteriorated. Arista joined the S&P 100 in September, according to the release, which reflects how large and widely owned the company has become. At around $186, the stock is back where it traded in late October rather than near its highs, and the guidance implies another record quarter. The questions for the coming months are whether hyperscaler capital budgets for 2027 hold up and whether gross margins stabilize around 64% as the customer mix keeps tilting toward the largest buyers.
Sources
- Arista Networks Q3 2026 earnings release (Form 8-K, Exhibit 99.1) — SEC EDGAR
- The Stock Market Today, November 3, 2026 — StockTitan
- Earnings Calendar for the Week of November 2, 2026 — StockTitan
- Arista Networks (ANET) quote and after-hours trading — Yahoo Finance
Market data: Yahoo Finance, close of 2026-11-03. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of November 4, 2026 and market data as of the 2026-11-03 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.