
November 4, 2026 | TickerRoast Markets Analysis
AMD delivered the kind of quarter the AI trade needed. Revenue rose 45% to a record $13.4 billion, data center sales nearly doubled, and the company guided to about $17 billion for the fourth quarter, well above what analysts expected. The stock rose about 5% after hours, a rebound for shares that had fallen more than a quarter from their October high.
A Record Quarter Above AMD’s Own Guidance
The headline figures in AMD’s third-quarter press release are strong across the board. Revenue reached $13.38 billion, up 45% from $9.25 billion a year earlier and up 16% from the second quarter. GAAP gross margin was 54% and non-GAAP gross margin 56%. Non-GAAP operating income reached $3.9 billion and non-GAAP earnings per share came in at $2.09, up 74% year over year according to chief financial officer Jean Hu. On a GAAP basis, AMD earned $2.4 billion, or $1.46 per share.
Expectations were lower. According to Investing.com, analysts had expected earnings of $1.94 per share on revenue of $13.06 billion, while Investopedia cited a Visible Alpha consensus of $13.1 billion in revenue. Chief executive Lisa Su said in the release that revenue exceeded the high end of the company’s guidance “as Data Center segment sales nearly doubled year-over-year.”
| Segment | Q3 2026 revenue | Year over year |
|---|---|---|
| Data Center | $8.5 billion (record) | +97% |
| Client | $2.9 billion | +7% |
| Gaming | $773 million | -40% |
| Embedded | $1.1 billion | +29% |
| Total | $13.4 billion | +45% |
Data Center Is Now Almost Two Thirds of the Business
The mix shift is the story I keep coming back to. Data center revenue of $8.55 billion represented roughly 64% of total sales, up from about 47% a year ago, based on the figures in AMD’s release. Gaming is the clear weak spot, down 40% to $773 million, but it is now small enough that its decline barely dents the group total.
The customer list explains the growth. AMD says Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are running models and workloads on the first Helios rack-scale systems, which combine Instinct MI450 Series GPUs with sixth-generation EPYC CPUs. Su said she expects growth to accelerate further in the fourth quarter “as we scale Helios and ‘Venice’ production,” Venice being the code name for the new EPYC generation. The release also lists the release of the ROCm 10 software stack, the selection of AMD hardware for Europe’s LUMI-AI supercomputer, and agreements to acquire World Labs and Taalas.
A $17 Billion Outlook Resets the Bar
The guidance is what moved the stock. AMD expects fourth-quarter revenue of about $17 billion, plus or minus 3%, which at the midpoint implies growth of about 66% year over year and 27% sequentially, with a non-GAAP gross margin of about 55%, according to the release. The consensus had been $16.23 billion, according to Investing.com. A sequential jump of that size is rare for a company of AMD’s scale and only makes sense if Helios shipments ramp quickly.
There is one number I would not ignore. The fourth-quarter margin guide of about 55% is a point below the third quarter’s 56%, which suggests the rack-scale systems ramping now carry lower margins than individual chips. It does not change the picture of demand, but it shows that growth on this scale has a cost, and it is the line I expect analysts to press on as Helios volumes grow.
The Stock Had Already Given Back a Lot
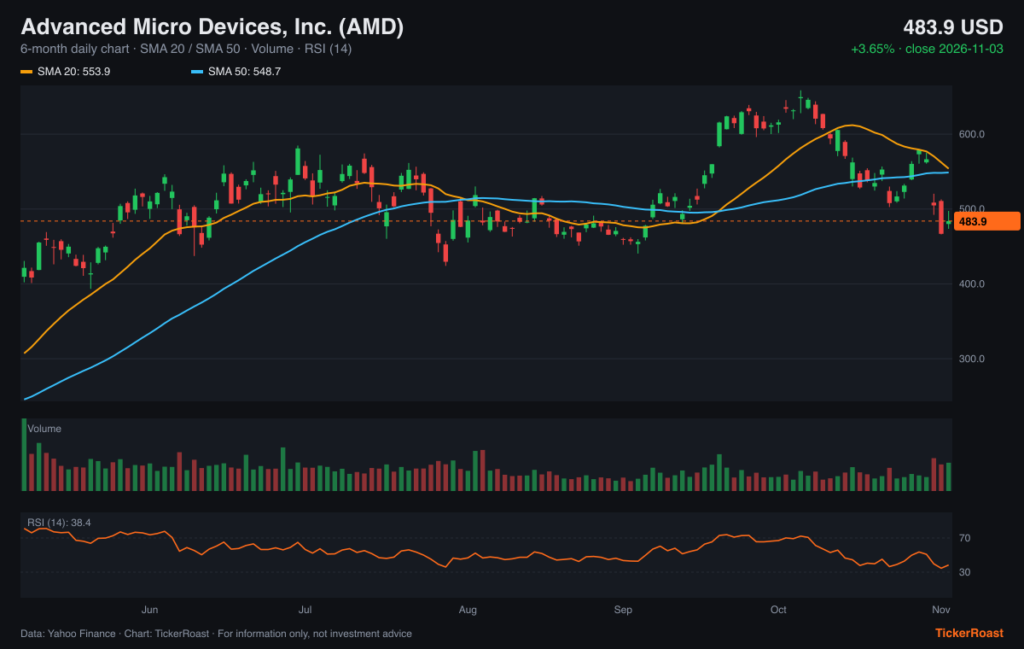
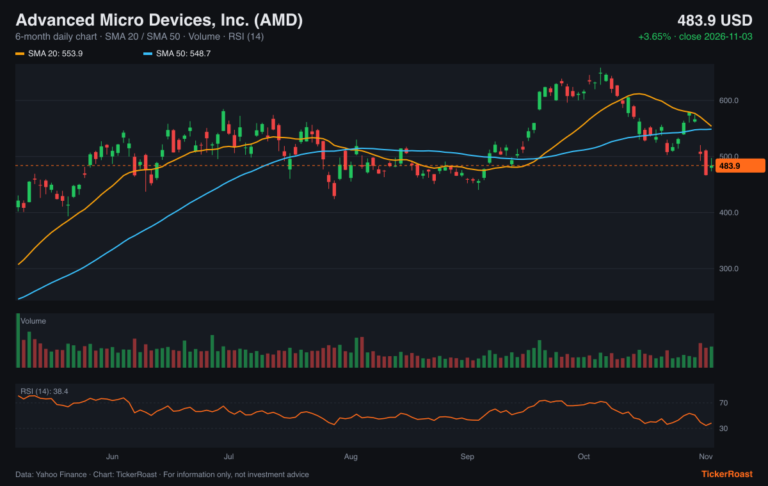
The chart shows AMD over the past six months with its moving averages, volume and RSI. The shares closed Tuesday at $483.90, up 3.65% on the day but about 25% below their October 6 high of $649.42, and below both the 20-day average near $554 and the 50-day average near $549. The 14-day RSI was about 36. The after-hours price of $508.20, about 5% higher according to Yahoo Finance, would still leave the stock below those short-term averages, though well above its 200-day average near $413. Investing.com noted that the shares fell 17.5% in October even though they had more than doubled this year.
That context matters for interpreting the reaction. A 5% gain after a report this strong is respectable rather than euphoric, and I think it reflects the same nervousness that has hit every AI hardware name in recent weeks: worries about how long hyperscalers can keep raising capital spending, Fed Chair Kevin Warsh’s warning that rates “get in the cracks,” and, since last night, a Democratic Senate that investors fear could be less friendly to the data center buildout.
What Comes Next
The next checkpoints are AMD’s appearances at investor conferences on December 1 and December 9, according to Investopedia, and above all the fourth-quarter report early next year, which will show whether Helios revenue arrives on the schedule implied by the $17 billion guide. For the rest of the sector, AMD’s results are a useful data point ahead of Qualcomm and Arm tonight: demand for AI accelerators clearly has not peaked, but the market is now asking about margins and cash flow as much as about growth.
Disclosure: this article mentions Anthropic as one of AMD’s customers. It was written with the assistance of Claude, an AI model developed by Anthropic, and is limited to facts reported by AMD and the cited sources.
Sources
- AMD Reports Third Quarter 2026 Financial Results — AMD
- AMD stock jumps after hours as quarterly results, revenue guidance beat estimates — Investing.com
- Markets News, Nov. 3, 2026 — Investopedia via Yahoo Finance
- AMD quote and after-hours trading — Yahoo Finance
- Fed Chair Kevin Warsh’s warning to AI investors — Fortune
Market data: Yahoo Finance, close of 2026-11-03. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of November 4, 2026 and market data as of the 2026-11-03 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.