
November 4, 2026 | TickerRoast Markets Analysis
AMD gave the battered chip sector the report it needed. Third-quarter revenue reached a record $13.4 billion, data center sales nearly doubled, and the company guided to about $17 billion for the fourth quarter. The stock rose about 7% in overnight trading even as index futures slipped on the election results.
A Record Quarter Above the Top of the Guidance
According to AMD’s earnings release, third-quarter revenue grew 45% year over year to $13.4 billion, which CEO Lisa Su said exceeded the high end of the company’s guidance. GAAP gross margin was 54% and GAAP diluted EPS was $1.46. On a non-GAAP basis, gross margin was 56%, operating income was $3.9 billion and diluted EPS was $2.09, up 74%. According to CNBC, analysts polled by LSEG expected adjusted earnings of $1.95 a share.
CFO Jean Hu pointed to operating leverage, and the numbers support that: earnings grew much faster than revenue because the incremental sales came largely from the data center business. That matters because the main worry around AI chipmakers in recent weeks has been margins and the sustainability of customer spending, not demand in the current quarter.
Data Center Sales Nearly Double
The data center segment produced record revenue of $8.5 billion, up 97% year over year, driven by EPYC server processors and the launch of the Instinct MI450 series GPUs. AMD said Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are running models and workloads on its first Helios rack-scale systems, which combine MI450 GPUs with sixth-generation EPYC CPUs. Su said AMD expects growth to accelerate further in the fourth quarter as it scales Helios and “Venice” production.
| Segment | Q3 2026 revenue | Year over year |
|---|---|---|
| Data Center | $8.5B | +97% |
| Client and Gaming | $3.7B | -8% |
| of which Client | $2.9B | +7% |
| of which Gaming | $773M | -40% |
| Embedded | $1.1B | +29% |
| Total | $13.4B | +45% |
The rest of the business is mixed. Client and Gaming revenue fell 8% to $3.7 billion, as a 7% increase in client processor sales was more than offset by a 40% drop in gaming revenue, which AMD attributed to lower semi-custom and graphics sales. Embedded revenue grew 29% to $1.1 billion, helped by aerospace and defense, automotive, communications and industrial markets.
A $17 Billion Guide Implies Acceleration
The outlook is the number the market reacted to. AMD expects fourth-quarter revenue of approximately $17 billion, plus or minus 3%, which it said represents year-over-year growth of about 66% and a sequential increase of about 27% at the midpoint, with non-GAAP gross margin of about 55%. CNBC reported that the revenue forecast came in above analysts’ estimates.
Two details stand out to me. First, a 27% sequential jump in a single quarter is unusual for a company of this size, and it depends on Helios shipments ramping on schedule. Second, the margin guide of 55% is one point below the third quarter, which in my reading could reflect a less favorable mix as the first rack-scale systems ship, although AMD did not break this out. Neither undermines the quarter, but both will be scrutinized as the year closes.
The Stock Rebounds From a Steep Pullback
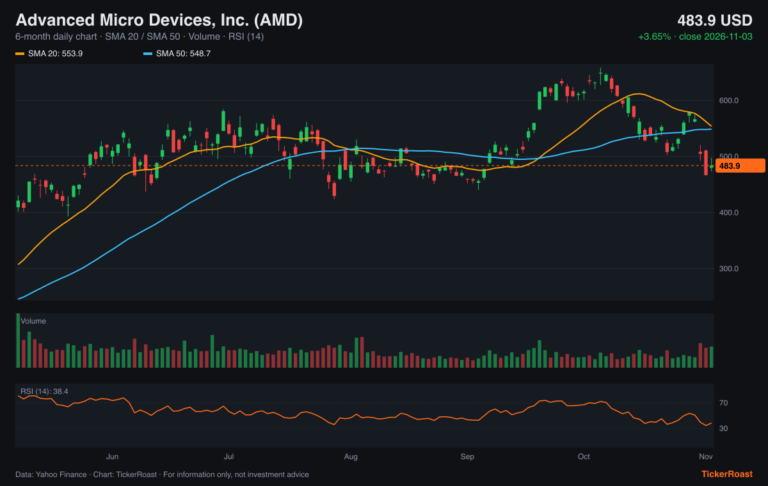
AMD closed Tuesday at $483.90, up 3.65%, ahead of the report, and traded at $520.49 in the overnight session at about 2:14 a.m. ET, up 7.56%, according to Yahoo Finance. CNBC reported that shares initially surged by double digits after the release before giving back part of the gain as index futures turned lower on the election results.
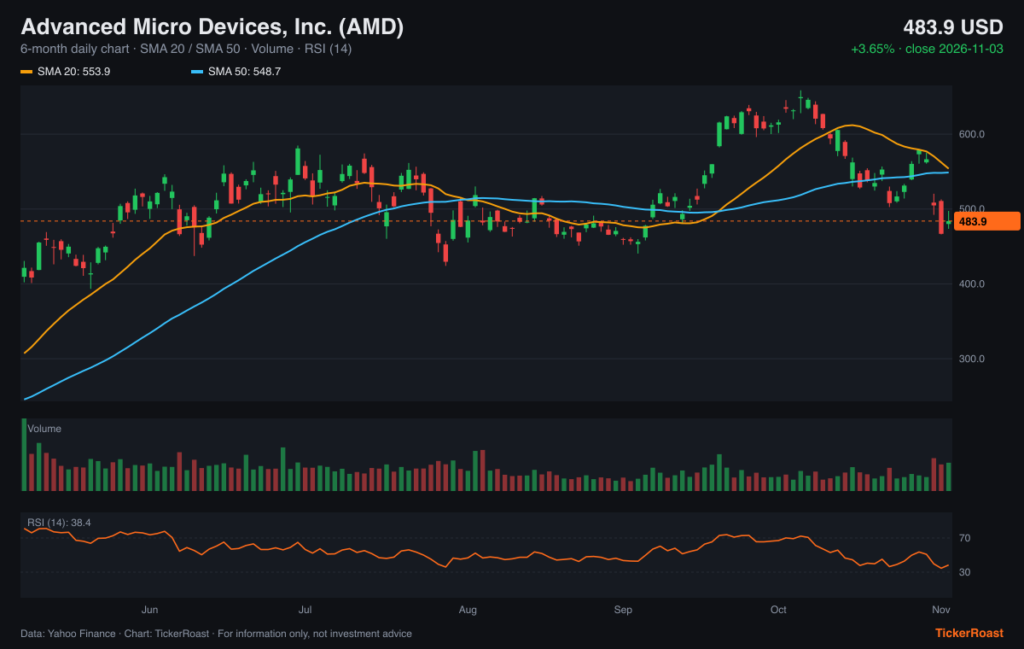
The rebound starts from a deep hole. According to Yahoo Finance data, the stock closed Tuesday about 25% below its 52-week high of $649.42, set on October 6, and below both its 20-day moving average near $554 and its 50-day average near $549, with the 14-day RSI around 38. Even if the overnight price of about $520 holds at the open, the shares would still sit below those two averages, which is the zone I would watch to judge whether this report changes the trend or simply interrupts the selloff.
Execution Now Matters More Than Demand
AMD’s release also lists proposed acquisitions of World Labs and Taalas among its forward-looking plans, a sign that the company keeps adding software and AI capabilities around its hardware. But the real test is operational: shipping enough Helios racks to hit a $17 billion quarter, while keeping margins near 55%, at a time when investors are questioning the pace of hyperscaler spending and the election has raised new questions about where data centers get built.
For now, AMD has done what Intel could not last week: it gave a forecast that points to acceleration rather than a slowdown. That is a useful data point for the rest of the sector ahead of Qualcomm and Arm tonight, even if it cannot by itself settle the broader debate over AI spending.
Disclosure: this article mentions Anthropic as one of AMD’s customers. It was written with the assistance of Claude, an AI model developed by Anthropic, and is limited to facts reported by AMD and the cited sources.
Sources
- AMD Reports Third Quarter 2026 Financial Results — AMD
- Stocks making the biggest moves after hours — CNBC
- Stock futures mixed as Democrats win big in midterms: Live updates — CNBC
- Stock market today: AMD beats Q3 estimates — Yahoo Finance
- AMD quote and history — Yahoo Finance
Market data: Yahoo Finance, close of 2026-11-03. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of November 4, 2026 and market data as of the 2026-11-03 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.