

October 30, 2026 | TickerRoast Markets Analysis
Amazon reported its fastest AWS growth in nearly five years and the highest operating margin in its history. Investors looked past both and focused on the bill: $77 billion of property and equipment purchases in a single quarter, a trailing free cash flow outflow of $42.4 billion and earnings per share slightly below expectations. The stock ended after-hours trading 7.3% lower.
Record Margins, Negative Cash
According to Amazon’s third-quarter release, net sales rose 12% to $201.9 billion and operating income climbed to $28.1 billion from $17.4 billion a year earlier, an operating margin of 13.9% that the company describes as its highest ever. AWS revenue grew 39% to $46.0 billion, and AWS operating income rose to $17.8 billion from $11.4 billion. On almost any operating metric, this was a strong quarter.
The cash flow statement tells a different story. Purchases of property and equipment reached $77.3 billion in the quarter, more than double the $35.1 billion of a year earlier. Operating cash flow over the trailing twelve months grew 29% to $168.3 billion, but net capital spending over the same period hit $210.7 billion, leaving free cash flow at an outflow of $42.4 billion versus an inflow of $14.8 billion a year ago. Amazon says the increase primarily reflects investments in artificial intelligence.
| Metric | Q3 2026 | Q3 2025 |
|---|---|---|
| Net sales | $201.9B | $180.2B |
| AWS sales | $46.0B (+39%) | $33.0B |
| Operating income | $28.1B | $17.4B |
| Operating margin | 13.9% | 9.7% |
| Diluted EPS | $1.89 | $1.95 |
| Purchases of property and equipment | $77.3B | $35.1B |
| Free cash flow, trailing 12 months | -$42.4B | +$14.8B |
Why Earnings Per Share Fell
Net income slipped to $20.7 billion, or $1.89 a share, from $21.2 billion, or $1.95. Amazon attributes the decline primarily to pre-tax gains of $9.5 billion that it booked in the third quarter of 2025 on its investments in Anthropic, which inflated the year-ago comparison. This quarter, non-operating items were a net expense of $1.2 billion, including interest expense of $1.7 billion, up from $538 million a year earlier as the company has borrowed more. According to Constellation Research, Wall Street expected earnings of $1.96 a share on revenue of $202.26 billion, so Amazon fell slightly short on both lines.
I would not overweight the per-share miss. Operating income was up 61% and the decline in net income is mostly about a one-off gain a year ago. The more relevant number for the stock is the gap between what Amazon earns from operations and what it is spending to build data centers.
AWS Is Running Faster Than in Years
The bullish case lives in the cloud segment. AWS growth accelerated for a fifth straight quarter on the release’s own figures, from 20% excluding currency effects in the third quarter of 2025 to 39% now, and Amazon puts the business at a $184 billion annualized revenue run rate. Chief executive Andy Jassy said in the release that the company projects AWS revenue growth of over 40% in both 2027 and 2028.
On the call, according to Constellation Research, Jassy said Amazon is installing an AI accelerator about every 14 seconds and that customers are absorbing capacity almost as fast as it is installed. He added that inference already accounts for well over half of AWS’s AI revenue and said Amazon intends to make its training capacity available outside AWS late in 2027. The release also notes that token volume on Bedrock, AWS’s inference service, grew nearly 17 times year over year.
Retail and Advertising Lose Momentum
Outside AWS, growth was softer, partly because of calendar effects. Amazon notes that Prime Day moved into the second quarter in most large countries this year, after taking place entirely in the third quarter in 2025, and says growth would have been about 400 basis points higher without that shift. Online store sales grew just 2% to $68.5 billion, and advertising revenue rose 11% to $19.6 billion, or 12% excluding currency, down from 22% to 26% in the previous five quarters. North America operating income still improved to $8.7 billion from $4.8 billion.
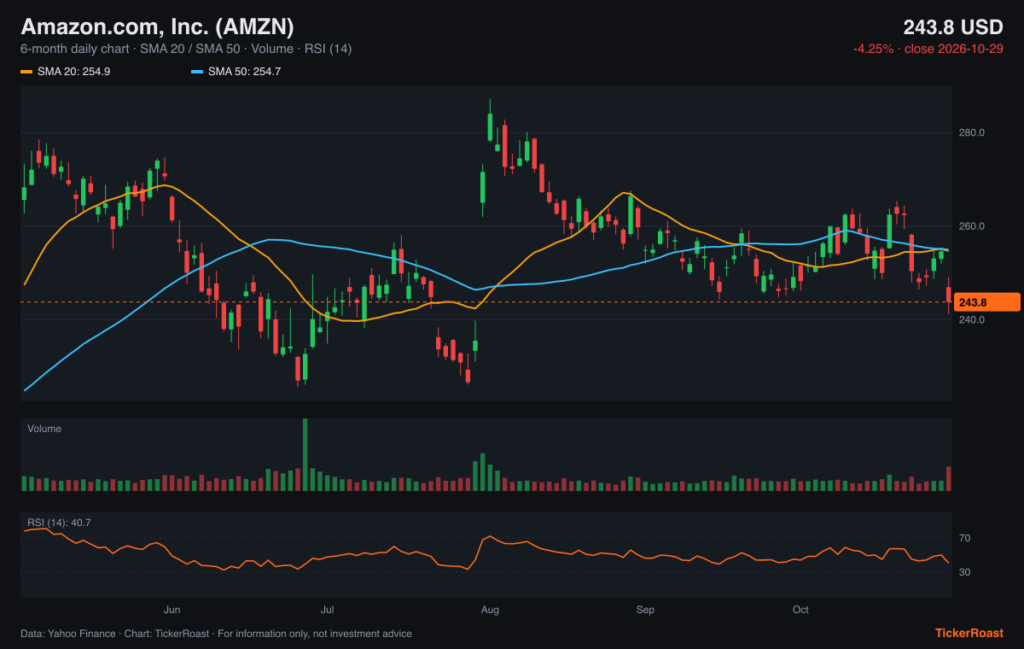
The chart shows Amazon’s six-month price action, moving averages, volume and RSI through Thursday’s regular-session close at $243.80, a 4.25% decline on the day, before the results were even released, on the heaviest volume since August. The stock finished below both its 20-day and 50-day moving averages, which sit close together near $255, and its RSI is around 41. A 7.3% after-hours decline would put the shares near $226, around the lows of late July that preceded the jump after last quarter’s report.
A Holiday Guide That Leaves Room for Debate
For the fourth quarter, Amazon expects net sales of $240.0 billion to $247.0 billion, growth of 12% to 16%, and operating income of $28.5 billion to $33.5 billion versus $25.0 billion a year earlier. It expects advertising growth to rebound into the high teens and continues to expect 2026 cash capital expenditures of approximately $220 billion. The guidance excludes any impact from energy derivative contract remeasurements, a reminder that Amazon has begun hedging the power its data centers need.
After Thursday’s close, the shares ended after-hours trading 7.30% below their regular-session price, according to Stock Titan. The reaction fits a pattern from this week: Alphabet was punished for negative free cash flow, while Microsoft, whose operating cash flow still covered its capital spending, held up far better. Amazon’s operating cash generation is growing, but not as fast as its spending, and it raised $48.1 billion of long-term debt in the third quarter alone, according to its cash flow statement.
What Has to Happen Next
For me, the key question is the payback period. Jassy argues that AWS investment will produce a much larger free-cash-flow business than anyone imagined a couple of years ago, and the 39% growth rate gives that argument some credibility. But with trailing free cash flow at minus $42 billion and full-year capex near $220 billion, investors now want evidence that margin and cash conversion improve as capacity comes online, not just that revenue grows. The fourth-quarter report in early 2027, and any first look at 2027 capital spending, will be the next real checkpoint.
This article was written with the assistance of Claude, developed by Anthropic. Anthropic is mentioned above because Amazon is an investor in the company.
Sources
- Amazon.com Announces Third Quarter Results — Amazon (SEC filing)
- AWS Q3 revenue growth surges 39%, capex stings Amazon’s cash flow — Constellation Research
- Stock Market Today, October 29, 2026: Nasdaq Falls as Alphabet Drops; Amazon and Intel Slide After Hours — Stock Titan
Market data: Yahoo Finance, close of 2026-10-29. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 30, 2026 and market data as of the 2026-10-29 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

