

October 29, 2026 | TickerRoast Markets Analysis
ServiceNow delivered what its chief executive called an inflection-point quarter, beating the top end of its guidance and lifting its AI contract target again. Investors focused instead on a slowdown in contracted revenue growth for the fourth quarter and a sharp drop in GAAP profitability, and the stock fell about 17% after hours.
A Beat That the Market Refused
According to the company’s third-quarter press release, subscription revenue rose 21% year over year to $3,988 million and total revenue rose 20.5% to $4,106 million. Current remaining performance obligations, the contracted revenue ServiceNow expects to recognize over the next 12 months, reached $13.65 billion, up 20.5%, while total remaining performance obligations grew 22% to $29.7 billion. The company says it beat the high end of its guidance on every topline growth and profitability metric.
The stock reaction told a different story. ServiceNow closed Wednesday’s regular session at $150.13, down 3%, and traded at $124.45 after hours, a drop of about 17.1%, according to Investing.com. AskTraders, citing Yahoo Finance consensus data, notes that non-GAAP earnings per share of $1.00 came in two cents below the $1.02 analysts expected, while revenue was roughly 0.4% ahead of the $4.09 billion consensus. A two-cent miss rarely explains a move of this size on its own; the guidance does.
The 18.5% Number
For the fourth quarter, ServiceNow guided subscription revenue to $4,245 million to $4,255 million, which it says represents 22.5% to 23% reported growth and 21.5% in constant currency. The figure that hit the stock was cRPO growth guidance of 18.5%, two points below the 20.5% just reported. Since cRPO is the closest thing investors have to a forward indicator for a subscription software company, a step down below 20% landed as a signal that growth is cooling heading into 2027.
Chief financial officer Gina Mastantuono pushed back on that reading on the call. According to the Investing.com transcript summary, she described cRPO as a nuanced accounting metric and said strong early renewals that were pulled forward from the fourth quarter accounted for about half of the third-quarter cRPO beat, which mechanically lowers the fourth-quarter comparison. She also cited a higher on-premises deal mix, worth about 25 basis points, and the exclusion of a backlog item worth about 50 basis points of growth. I find the timing explanation plausible, but it is the kind of argument investors tend to want confirmed by the next quarter’s numbers rather than accept on faith.
GAAP Profit Takes a Hit
The second pressure point is profitability. The press release shows GAAP net income of $277 million, or $0.27 per diluted share, down from $502 million a year earlier. GAAP operating margin fell to 9.5% from 17%. The non-GAAP operating margin held up better at 32.5%, versus 33.5% a year ago, but the gap between the two measures has widened considerably.
| Metric | Q3 2026 | Q3 2025 |
|---|---|---|
| Total revenue | $4,106M | +20.5% y/y |
| Subscription revenue | $3,988M | +21% y/y |
| GAAP net income | $277M | $502M |
| GAAP operating margin | 9.5% | 17% |
| Non-GAAP operating margin | 32.5% | 33.5% |
| Amortization of purchased intangibles | $198M | $33M |
| Free cash flow margin | 20% | 17.5% |
The table explains most of that gap. Amortization of purchased intangibles rose to $198 million from $33 million, reflecting the company’s acquisitions, which the call identified as including Armis, Veza, Moveworks and Logik.ai. Stock-based compensation climbed to $633 million from $492 million, and severance costs rose to $87 million from $24 million. The GAAP subscription gross margin fell to 73.5% from 80%. These are largely non-cash or one-time items, but they show that ServiceNow has been buying growth, and the bill is now visible in the income statement.
The AI Story Is Getting Bigger
None of this erases what management sees as the real story. ServiceNow raised its target for AI annual contract value in 2026 to $1.7 billion, from $1 billion at the start of the year, and says year-to-date consumption of agentic AI in production is up more than 13 times from a year earlier. According to the Investing.com summary, AI net new ACV grew 65% year over year in the quarter and AI deals above $1 million grew 4.5 times. The company also counted 19 transactions above $5 million in net new ACV, up more than 135%, and 680 customers paying more than $5 million a year.
The company is also leaning into partnerships, including an expanded agreement with OpenAI announced alongside the results and a new Control Tower Alliance of AI, cloud and security vendors. Chief executive Bill McDermott framed ServiceNow as a governance layer for enterprise AI and pointed out that, unlike the hyperscalers, it does not face capital or compute constraints.
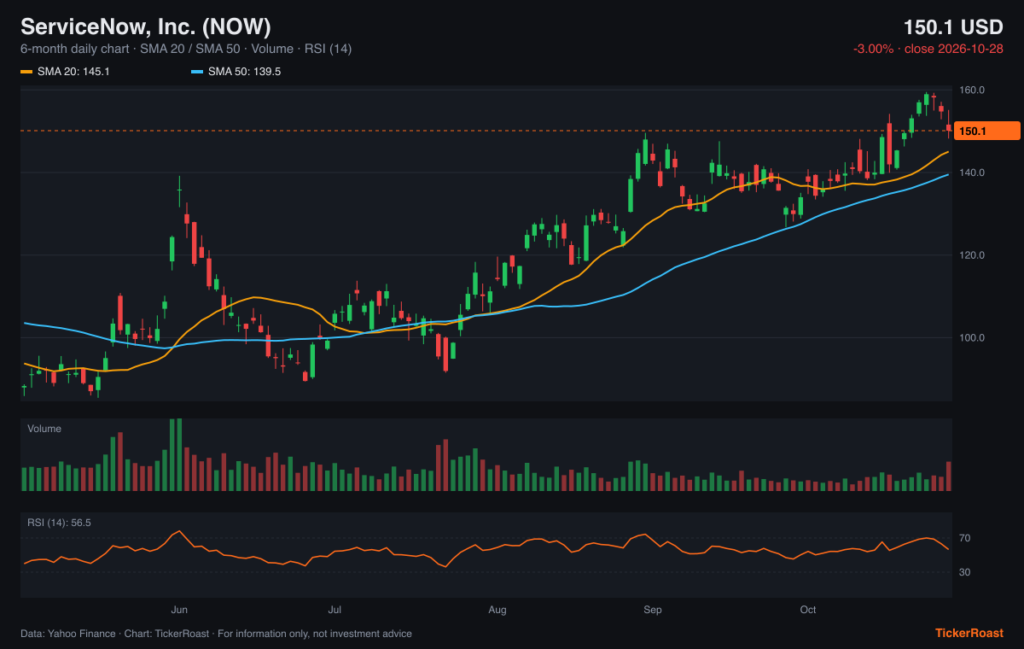
The chart shows ServiceNow’s six-month price action, moving averages, volume and RSI through Wednesday’s regular-session close, before the after-hours decline. The stock closed at $150.13, above its 20-day average near $145 and its 50-day average near $140, after a steady climb since July. An after-hours price around $124 would put it below both averages and erase most of the gains since August. AskTraders notes that the shares had risen about 63% since July 23 going into the report, which helps explain why a quarter that beat guidance was not enough.
Cash Flow Is the Counterargument
The one area where guidance moved clearly up is cash. ServiceNow raised its full-year free cash flow margin target by 100 basis points to 36%, citing lower capital spending. Third-quarter free cash flow was $822 million, or a 20% margin, up from 17.5% a year earlier. Full-year subscription revenue guidance now stands at $15,780 million to $15,790 million, with a non-GAAP operating margin of 31.5%.
For me, the question going into the next few quarters is whether the AI contract momentum starts to show up in cRPO growth rather than only in the AI-specific metrics management highlights. If the pulled-forward renewals explain the fourth-quarter dip, the first-quarter guide in January should show growth reaccelerating. If it does not, the market’s reaction last night will look less like an overreaction and more like an early read on a maturing growth profile. ServiceNow executives are scheduled to speak at BMO’s technology conference on Nov. 12, the first chance to hear how management responds to the selloff.
Sources
- ServiceNow Reports Third Quarter 2026 Financial Results — ServiceNow (SEC filing)
- Earnings call transcript: ServiceNow Q3 2026 revenue beats, shares sink after hours — Investing.com
- ServiceNow Stock Plunges After Hours Following Q3 Results — AskTraders
Market data: Yahoo Finance, close of 2026-10-28. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 29, 2026 and market data as of the 2026-10-28 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

