

October 29, 2026 | TickerRoast Markets Analysis
Chipotle missed on earnings and reported thinner margins, but investors cared more about one number: comparable restaurant sales rose 2.1%, helped by a third straight quarter of positive traffic. The shares rose about 7% in extended trading.
Traffic Is the Story Investors Wanted
Chipotle’s third-quarter release shows total revenue up 9.6% to $3.3 billion and comparable restaurant sales up 2.1%. That comparable figure breaks down into a 1.3% increase in average check and a 0.8% increase in transactions. According to GuruFocus, analysts surveyed by LSEG had expected same-store sales growth of 1.5%.
The headline in the press release says it plainly: this is the third consecutive quarter of positive transaction growth. For a chain that spent much of the past year fighting the perception that diners were pulling back, I think that matters more than the earnings line. Chipotle shares closed Wednesday’s regular session up 2.82% at $28.77 and rose 6.89% to $30.71 after hours, according to Investing.com, while Stock Titan recorded a gain of 7.1% at 6:02 p.m. Eastern.
Margins Moved the Wrong Way
The profit picture was weaker. Operating margin fell to 13.7% from 15.9% and restaurant-level operating margin dropped to 23.3% from 24.5%. Net income was $339.9 million, or $0.27 per diluted share, compared with $382.1 million, or $0.29, a year earlier. Investing.com puts the consensus at $0.29 per share, so the quarter was a miss on earnings.
| Metric | Q3 2026 | Q3 2025 |
|---|---|---|
| Total revenue | $3.3B | +9.6% y/y |
| Comparable restaurant sales | +2.1% | n/a |
| Food, beverage and packaging (% of revenue) | 29.5% | 30.0% |
| Labor (% of revenue) | 25.7% | 25.2% |
| Restaurant-level operating margin | 23.3% | 24.5% |
| Operating margin | 13.7% | 15.9% |
| Diluted EPS | $0.27 | $0.29 |
Food costs were not the problem. Food, beverage and packaging fell to 29.5% of revenue from 30.0%, as menu price increases, tariff relief and a favorable mix of limited-time offers outweighed inflation in beef and freight. Labor was the pressure point, rising to 25.7% of revenue from 25.2% on wage inflation, performance bonuses, extra staffing for promotions and higher insurance costs. General and administrative expenses rose to $185.2 million from $146.7 million, driven by stock-based compensation, bonuses and corporate initiatives, and the effective tax rate climbed to 25.6% from 23.1%.
October Was Softer, Then Recovered
The call added some nuance to the optimism. According to the Investing.com transcript summary, management said October trends softened in line with the broader industry before transactions turned positive again. Chipotle expects fourth-quarter comparable sales of around 2%, with an exit rate of 3% to 4%. Menu pricing contributed about 2.7% in the third quarter and is expected to reach about 3% in the fourth, and management expects cost of sales near 30.5% in the fourth quarter, mainly because of its Smoked Brisket promotion.
The full-year outlook in the release is unchanged: comparable sales growth in the low single digits and 350 to 370 new restaurants, including 10 to 15 international partner-operated locations. I read the unchanged guidance as a sign that management is comfortable with the trajectory, but not yet willing to call a sustained acceleration.
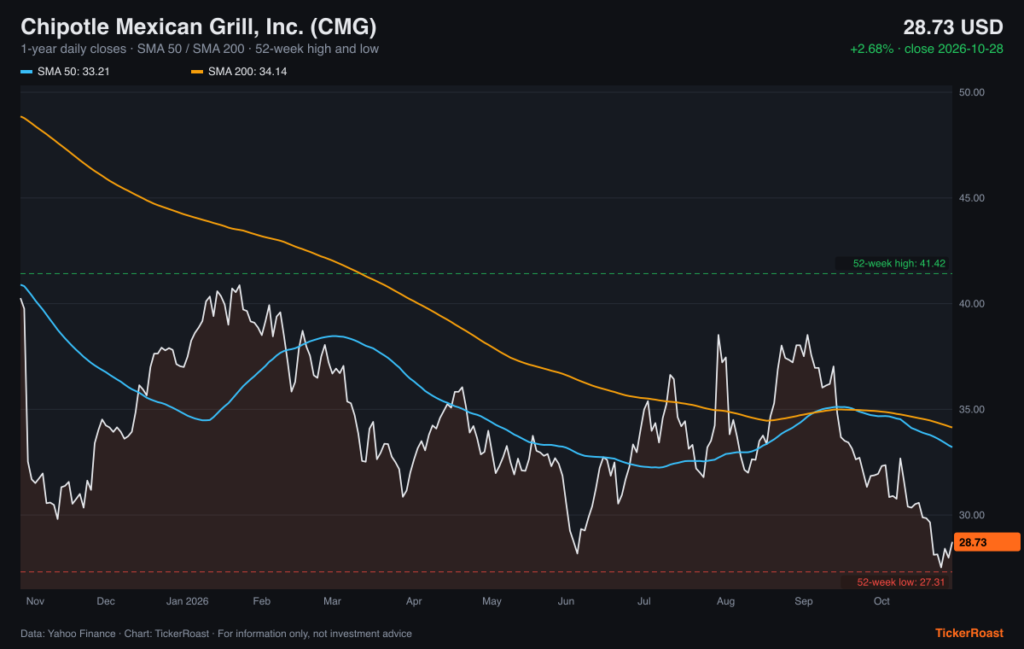
The chart above shows Chipotle’s one-year price history with its 50-day and 200-day moving averages and 52-week range, through Wednesday’s regular-session close. It does not include the after-hours gain. The picture is weak: the stock closed near $28.73 on the chart’s data, below its 50-day average of about $33.21 and its 200-day average of about $34.14, and not far above its 52-week low of $27.31. Both averages are sloping down. Even a 7% after-hours gain would leave the shares below those trend lines, which is why I would describe last night’s move as relief rather than a change in trend.
Building Capacity Rather Than Raising Prices
Chipotle’s strategy rests on throughput and new units more than on pricing. The company opened 84 company-owned restaurants in the quarter, 53 of them with a Chipotlane drive-through pickup lane, and five international partner-operated locations. Per the call summary, the high-efficiency equipment package is now in more than 1,700 restaurants, targeting about 2,000 by year-end, and lets a restaurant handle roughly two more entrees in the peak 15-minute window. Digital sales reached 38.8% of food and beverage revenue, up from 36.7%.
International expansion is accelerating as well. Chipotle entered Mexico, Saudi Arabia and South Korea during the quarter, according to the call summary. For 2027, the release calls for 340 to 360 new company-owned restaurants in the U.S. and Canada and about 15 to 25 restaurants outside those markets.
Buybacks Continue at Lower Prices
The company repurchased $110 million of stock in the quarter at an average price of $34.05, according to the release, about 18% above where the shares closed before the report. That leaves $1.6 billion under existing repurchase authorizations.
Chipotle’s challenge for the next few quarters is to turn modest positive traffic into margin recovery. Labor costs and promotional spending are eating into the benefit of higher prices, and management is guiding to a slightly higher food cost ratio in the fourth quarter. If the 3% to 4% exit rate holds into early 2027, the operating leverage case gets easier to make. For now, the market is rewarding the direction of traffic rather than the level of profit.
Sources
- Chipotle Announces Third Quarter 2026 Results — Chipotle Mexican Grill (SEC filing)
- Earnings call transcript: Chipotle beats revenue in Q3 2026, shares jump after hours — Investing.com
- Chipotle Mexican Grill Shares Rise After Positive Comparable Sales Growth Report — GuruFocus
- Stock Market Today Live October 28, 2026 — Stock Titan
Market data: Yahoo Finance, close of 2026-10-28. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 29, 2026 and market data as of the 2026-10-28 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

