

October 29, 2026 | TickerRoast Markets Analysis
Wall Street wakes up on Thursday with a split verdict on Big Tech, a heavy data morning and the busiest earnings calendar of the week. Alphabet is dragging the Nasdaq lower before the open, Microsoft is moving the other way, and the third-quarter GDP and September PCE reports arrive within minutes of each other.
A Quiet Gain After a Loud Fed
The S&P 500 rose 0.28% on Wednesday to 7,743.98, the Nasdaq Composite added 0.27% to 26,549.85 and the Dow Jones Industrial Average gained 0.19% to 52,475.10, according to The Motley Fool. It was a third straight gain for the S&P 500, but the more interesting action was beneath the surface. Oracle rose about 11% after its investor day and Vertiv jumped almost 17%, while F5 fell more than 20% on its guidance and a downgrade.
The Federal Reserve held its target range at 3.75% to 4% in a 10-2 vote, with Governor Lisa Cook and Cleveland Fed President Beth Hammack preferring a quarter-point hike, as reported by Stock Titan and others. I covered the decision in detail yesterday; what matters this morning is that two hawkish dissents make every inflation print between now and December more consequential, and today brings one of the most important.
The 10-year Treasury yield closed at 5.02%, according to The Motley Fool, crossing the 5% line. The Associated Press, in a report carried by AOL, says the 10-year eased back below 5% overnight after touching about 5.04% on Wednesday, while the 2-year yield slipped to 4.68%.
After Hours Rewrote the Tape
Extended trading was far more volatile than the session itself. According to Stock Titan, as of 6:02 p.m. Eastern Alphabet’s class A shares were down 10.8%, Fortinet was down 26.2%, Microsoft was up 4.9% and Chipotle was up 7.1%. Stock Titan also flagged Sprouts Farmers Market down 21.1%, Lumentum up 11.6% and Marvell Technology down 7.4%. ServiceNow fell about 17% after hours, per an earnings call write-up on Investing.com, despite results that beat its own guidance.
Microsoft, ServiceNow, Chipotle and Fortinet each get their own analysis on TickerRoast this morning. Alphabet was covered last night. Ford also reported after the close and raised the low end of its full-year adjusted EBIT guidance to a range of $10.5 billion to $11 billion, according to its press release.
Futures Lean on the Nasdaq
The damage is concentrated in technology. HDFC Sky reported Nasdaq futures down 1.4% in early Asian trade. That move largely reflects Alphabet’s weight in the Nasdaq 100; Microsoft’s gain only partly offsets it. I would treat the opening print with caution, because the GDP and PCE numbers at 8:30 a.m. can easily reset the tone before the bell.
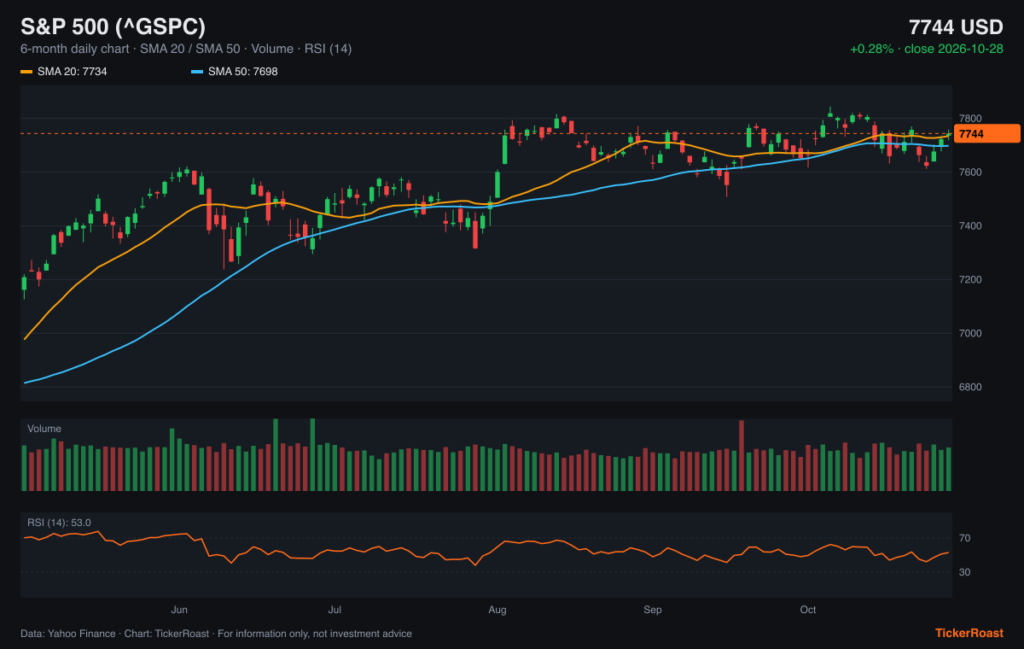
The chart above shows the S&P 500 over the last six months with its moving averages, volume and RSI, as of Wednesday’s close. The index finished at 7,744, just above its 20-day average near 7,734 and its 50-day average near 7,698, with an RSI of 53 that sits in neutral territory. In other words, the trend is intact but flat, and the index has been trading in a narrow band since August. It does not yet reflect this morning’s futures weakness.
Asia Splits Along Chip Lines
Asian markets were mixed. The AP reports that Japan’s Nikkei 225 edged up 0.2% to 64,073.17 while South Korea’s Kospi lost 2.2% to 5,880.25, Taiwan’s Taiex fell 1.9%, the Shanghai Composite slipped 0.9% and Hong Kong’s Hang Seng was roughly flat. Samsung Electronics sank 5.4% despite strong results, because its shareholder return plans disappointed some investors, according to the same report. SK hynix rose 1.6% after a 10.9% jump the day before.
Oil Eases, but From a Very High Level
Crude prices dipped overnight. The AP puts WTI down 1.3% at $101.46 a barrel and Brent down 1.2% at $110.32, while HDFC Sky quotes Brent down 0.6% near $114.6, a gap that likely reflects different contract months. Either way, Brent remains far above the roughly $72 a barrel it traded at before the Iran war began in late February, per the AP. The same report says U.S. officials have warned that renewed military action against Iran could come after the Nov. 3 midterm elections, which keeps a risk premium in the price even as peace talk headlines come and go.
8:30 a.m.: GDP and PCE Together
The Bureau of Economic Analysis publishes the advance estimate of third-quarter GDP and the September personal income and outlays report, which contains the PCE price index, at 8:30 a.m. Eastern, according to the BEA release schedule. Having the growth number and the Fed’s preferred inflation gauge land together is unusual, and it creates an uncomfortable scenario for bond markets if both run hot. With the 10-year already hovering around 5%, I think the PCE figure matters more for stocks this morning than the growth headline.
Across the Atlantic, the European Central Bank’s Governing Council concludes its monetary policy meeting in Frankfurt today, followed by a press conference, according to the ECB calendar. The Bank of Japan wraps up its own meeting on Friday and is expected to hold, per the AP.
Earnings: Lilly, Mastercard and Caterpillar Before the Open, Amazon and Intel After
Eli Lilly, Mastercard and Shell report before the open, and Amazon and Intel report after the close, according to FX Leaders, which lists consensus earnings per share of $6.61 for Lilly, $5.17 for Mastercard, $1.96 for Amazon and $0.40 for Intel. Caterpillar is also on the morning slate. Amazon is the headline: after Alphabet’s ad miss and Microsoft’s Azure acceleration, investors will want to know which side of that split AWS lands on, and how much more Amazon plans to spend on data centers.
The Rest of the Week
Friday brings the Bank of Japan decision and the quarterly reports from ExxonMobil and Chevron, which will be read against crude prices that remain well above last winter’s levels. Next week the focus shifts to the Nov. 3 midterm elections and the October jobs report, the last major labor print before the Fed’s December meeting.
Sources
- Stock Market Today, Oct. 28: Markets Edge Higher as Fed Holds Rates Steady — The Motley Fool
- Stock Market Today Live October 28, 2026 — Stock Titan
- Asian shares and U.S. futures are mixed after Alphabet’s earnings disappoint — Associated Press via AOL
- Global Markets Today, October 29, 2026 — HDFC Sky
- BEA news release schedule — U.S. Bureau of Economic Analysis
- Meetings of the Governing Council — European Central Bank
- Forex Signals Oct 29: Amazon, Eli Lilly, Mastercard, Intel, Shell Earnings Preview — FX Leaders
- Ford Reports Third-Quarter 2026 Financial Results — Ford Motor Company (SEC filing)
Market data: Yahoo Finance, close of 2026-10-28. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 29, 2026 and market data as of the 2026-10-28 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

