

October 28, 2026 | TickerRoast Markets Analysis
Wall Street starts Wednesday with a rate decision at 2 p.m. Eastern, oil climbing again and the two biggest cloud earnings reports of the week still to come. Here is what moved overnight and what to watch.
Chips Carried Tuesday’s Rally
The S&P 500 rose 0.60% on Tuesday, the Nasdaq Composite gained 1.18% and the Dow Jones Industrial Average edged up 0.03%, according to TipRanks. Chip stocks led after Broadcom said a group of banks would provide $63 billion in financing for chips and networking products leased to Anthropic. The Philadelphia Semiconductor Index gained 3.6% for a third straight session, and, according to a market wrap on Substack, it is still more than 20% below its June 22 record close even after rising 62.1% this year, against 12.8% for the S&P 500.
Breadth was healthy without being euphoric. Advancers beat decliners by roughly 1.8 to 1 on both the NYSE and the Nasdaq, but volume of 16.1 billion shares was below the 20-day average of 17.18 billion, per the same wrap. Among individual names, UPS rose 5.8% and Royal Caribbean 5.5%, while Xylem fell 14.2% and Boeing 10.7% after their reports. Meta slipped 1.6% as investors weighed the $97.5 billion equity offering that Schwab notes includes a $3 billion investment from Nvidia.
Futures Are Flat to Mixed, and Oil Is the Wild Card
As of 1:30 a.m. Eastern, Nasdaq 100 futures were up 0.36%, S&P 500 futures were up 0.03% and Dow futures were down 0.21%, per TipRanks. The more important number is crude. Brent rose 1.48% to $115.57 a barrel and WTI gained 1.47% to $101.37 after an attack on a Saudi Arabian refinery. Tuesday’s settlements, at $113.88 for Brent and $99.90 for WTI, were each down about 1.7% to 1.8%, so the overnight move is a reversal of that dip rather than a new breakout. Still, a barrel of WTI above $100 keeps the inflation conversation at the center of today’s Fed meeting.
The 10-year Treasury yield closed Tuesday at 4.99%. A reading that close to 5% is the number I would watch if the Fed’s tone turns harder this afternoon.
Asia Rallied on Memory Profits
Asian markets took their cue from the chip trade. South Korea’s KOSPI jumped 5.7% in early trading, the Nikkei 225 added 1.3% and the MSCI Asia-Pacific ex-Japan index rose 1.6%, according to HDFC Sky. The catalyst was SK hynix, which reported a third-quarter operating profit of 83.3 trillion won, a more than seven-fold increase from a year earlier. We look at those numbers in detail in a separate analysis today.
The Fed Meeting Ends Today, With a Hold Expected
The Federal Open Market Committee announces its decision at 2 p.m. Eastern. The consensus is for no change in the 3.75% to 4.00% target range. Schwab reports that, according to CME FedWatch, the odds of a hike at this meeting were below 10%, while the odds of a December hike had eased to about 80% from a peak near 90%. The Fed raised rates last month for the first time in three years, and September consumer and producer inflation ran hot. Chair Kevin Warsh’s press conference is therefore the real event: markets want to know whether a December move is a base case or a possibility.
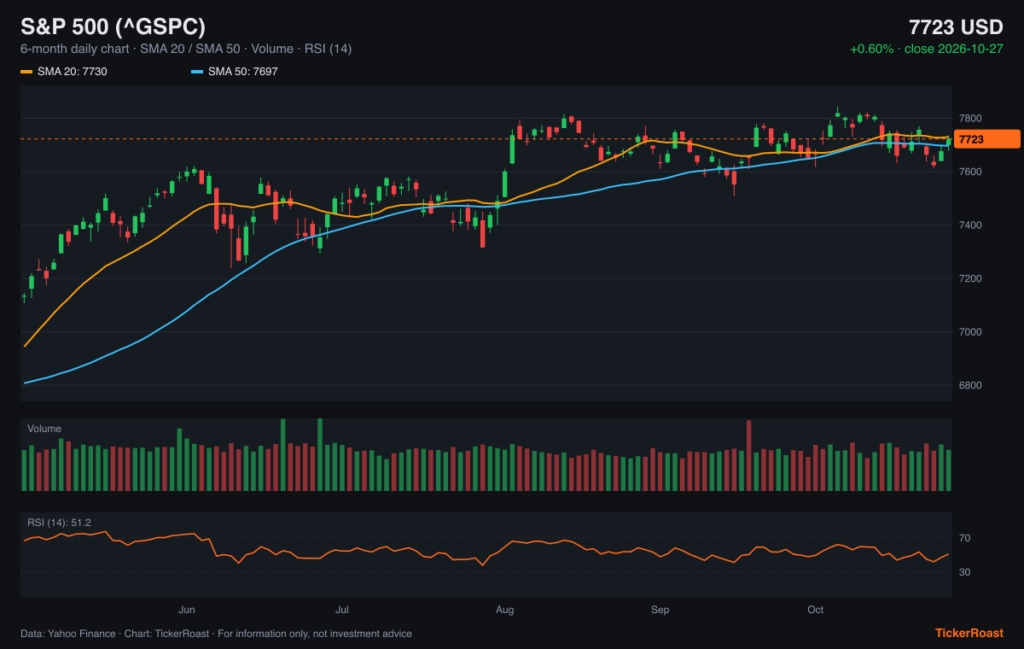
The chart above shows the S&P 500 against its moving averages heading into the decision. Schwab noted that 54.1% of S&P 500 stocks were above their 50-day average, up from 19.7% in late September but well below the July high of 73.9%, a sign that the recovery is broadening without having fully repaired the damage.
Earnings: Microsoft and Alphabet After the Close
Alphabet reports after the close with a call at 4:30 p.m. Eastern, and Microsoft follows with its fiscal first-quarter 2027 results and a 5:30 p.m. call, per Tech Insider. Schwab says the focus will be AI capital spending, financing and free cash flow. Also on today’s calendar are ServiceNow, Ford, Etsy, Teladoc and Chipotle, along with T-Mobile, GE Vernova, Amphenol, UBS, Phillips 66 and Vertiv.
Overnight, two reports from Tuesday’s after-hours session set a cautious tone for parts of the market. Robinhood fell about 8% in extended trading on its third-quarter results, per TipRanks, and Visa and Seagate also traded lower after their reports. Each gets its own analysis on TickerRoast today.
The Rest of the Week
Thursday brings the first estimate of third-quarter GDP, which analysts surveyed by Schwab expect at 3%, up from 2.2% in the second quarter, together with September PCE inflation and the European Central Bank decision. Amazon, Intel, Mastercard, Eli Lilly, Caterpillar and Starbucks report that day. Friday has the Bank of Japan, ExxonMobil and Chevron, and the October jobs report arrives a week from Friday.
Sources
- Futures Trade Mixed Ahead of Big Tech Earnings and the Fed’s Rate Decision — TipRanks
- Stocks Up, Oil Down Ahead of Earnings Blitz, Fed — Charles Schwab
- Relief Rally, Hold the Confetti — Substack
- Global Markets Today, October 28, 2026 — HDFC Sky
- Futures Mixed as 3 Events Hit: Fed, MSFT, Google — Tech Insider
Market data: Yahoo Finance, close of 2026-10-27. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 28, 2026 and market data as of the 2026-10-27 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

