

October 27, 2026 | TickerRoast Markets Analysis
UPS is shipping fewer packages and earning more on each one. Its third-quarter results, released on October 27, 2026, beat expectations, and management raised its full-year guidance. For me, this report is the clearest evidence so far that the strategy of deliberately shrinking low-margin volume, Amazon included, is starting to work.
Fewer Pieces, Higher Prices
According to the earnings release filed with the SEC, consolidated revenue rose 6.7% to $22.9 billion, and adjusted EPS came in at $1.69, a figure that analysts widely described as a beat. In the U.S. Domestic segment, average daily volume fell to 15.6 million pieces from 16.2 million, but revenue per piece rose 6.1%, pushing segment revenue up 4.5% to $14.9 billion.
This is the trade UPS chose when it announced it would cut the volume it handles for Amazon by roughly half. Losing pieces hurts network density, but the packages that remain pay more. The adjusted operating margin in U.S. Domestic stands at 7.0%, which is still thin for this business, and that is why I don’t consider the turnaround finished.
| Segment | Revenue | Growth | Adjusted operating margin |
|---|---|---|---|
| U.S. Domestic | $14.9B | +4.5% | 7.0% |
| International | $5.0B | +7.1% | 14.9% |
| Supply Chain Solutions | $3.0B | +18.2% | 9.2% |
| Total | $22.9B | +6.7% | 9.0% |
International and Logistics Pull Their Weight
International revenue grew 7.1% to $5.0 billion with revenue per piece up 15%, and its 14.9% margin remains the best in the group. Supply Chain Solutions grew 18.2% on forwarding and logistics, including healthcare, but it also produced the quarter’s main blemish: a $182 million goodwill impairment. Together with transformation costs and a small gain on MD-11 assets, it explains the gap between GAAP EPS of $1.37 and the adjusted $1.69. I also note that adjusted EPS is slightly below the $1.74 of a year ago, so the beat came against modest expectations.
A Higher Bar for the Peak Season
UPS now expects full-year revenue of about $92.6 billion, adjusted operating profit of about $8.75 billion, adjusted EPS of about $7.28 and adjusted free cash flow of about $6.1 billion. That implies a fourth quarter with roughly $25.7 billion of revenue and $3.3 billion of adjusted operating profit. Dividend payments are expected to total about $5.4 billion, subject to board approval, and capital spending about $3.0 billion. CEO Carol Tomé said that “given the strength we see in the business, we are raising our full-year financial guidance.”
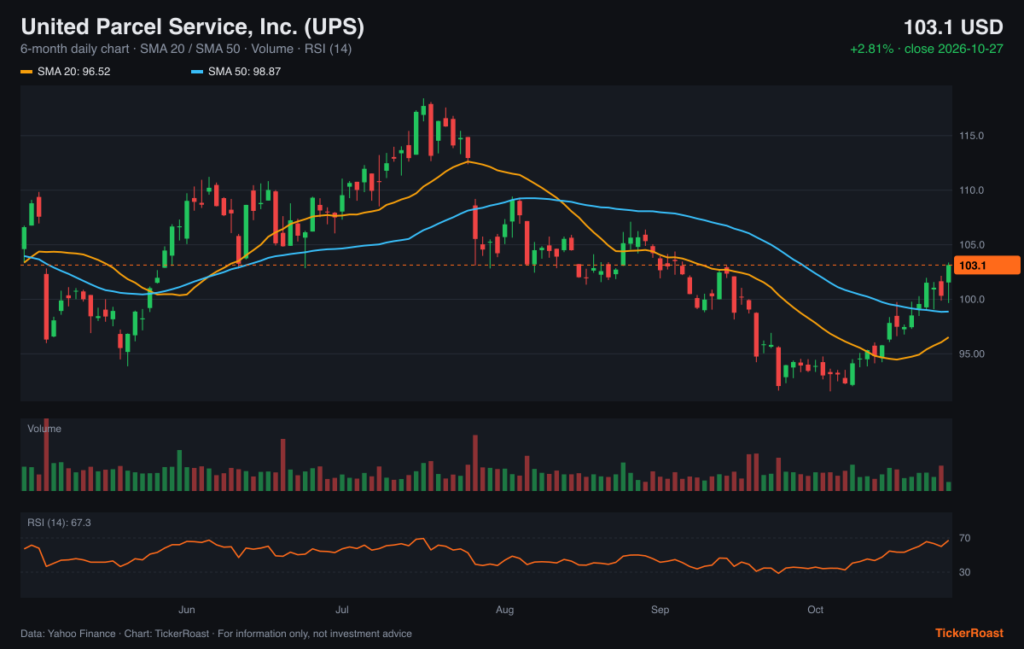
Yahoo Finance reported the shares up about 2% on Tuesday, with Tomé describing U.S. consumers as resilient heading into the holidays. I find that comment worth weighing against the numbers: free cash flow of $6.1 billion covers the $5.4 billion dividend, but without a wide margin. The holiday peak will test whether the leaner network can absorb a surge in volume without the costs that hurt margins in past years, and the January report will be the first full read on that.
Sources
- UPS Third Quarter 2026 Earnings Release (Form 8-K, Exhibit 99.1) — UPS / SEC
- Earnings live updates (UPS, Boeing, Coca-Cola) — Yahoo Finance
- UPS slashing Amazon volume by 50% in push for profitability — FreightWaves
Market data: Yahoo Finance, close of 2026-10-27. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 27, 2026 and market data as of the 2026-10-27 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

