

October 28, 2026 | TickerRoast Markets Analysis
Seagate reported record profitability on Tuesday afternoon and guided above its own results, and the stock still moved lower in extended trading. The numbers show a company selling more hard drives at better prices to AI data centers; the market reaction shows how much of that was already expected.
A 61% Jump in Revenue and a Record Margin
Seagate’s fiscal first-quarter 2027 revenue was $4.23 billion, up about 61% from a year earlier and 17% from the prior quarter, according to a summary of the earnings call on Yahoo Finance. Adjusted earnings per share were a record $7.68. 24/7 Wall St. put consensus at $7.40 for EPS and $4.14 billion for revenue, so the company beat by roughly 4% on earnings and 2% on sales, its fifth consecutive earnings beat. Non-GAAP operating margin reached a record 50.7%.
Data center customers were the story. Data-center revenue was $3.4 billion, up 63% year over year and 81% of the total. Edge and IoT revenue was $784 million, up 52%. Seagate shipped 220 exabytes in the quarter, of which 198 exabytes, or 90%, went to data-center customers. Exabyte growth from the prior quarter was modest, which management attributed to product transitions and qualification timing rather than yield or readiness problems.
Mozaic and the Price of Capacity
Revenue is growing faster than exabytes because each drive carries more capacity and commands better pricing. Seagate’s Mozaic platform, built on heat-assisted magnetic recording (HAMR), is the vehicle. Management said Mozaic 4, with up to 44 terabytes per drive, is ramping with two leading cloud providers and that more qualifications are expected over the next several months. HAMR is expected to account for about half of nearline exabyte shipments exiting calendar 2026, with Mozaic 4 making up about half of HAMR volume. The next step, Mozaic 5, offers more than 50 terabytes on a 10-disk platform, with qualification shipments expected near the end of calendar 2027.
On pricing, executives said value-based pricing is improving, partly offset by higher external component costs. The company targets mid-20% compound annual growth in nearline exabyte supply, driven mostly by higher capacity per disk rather than more disks. That discipline helps explain a 50.7% operating margin in a business that was long regarded as cyclical.
Demand That Is Already Spoken For
The most interesting comment came from the supply side. According to the call summary, the vast majority of nearline exabyte supply is allocated through calendar 2028, with some cloud agreements extending through 2030. Chief Executive Dave Mosley reported no sign of demand destruction or cancellations and said, in the summary’s wording, that everything Seagate can make above its plans is being spoken for. That mirrors what SK hynix said about memory this week: multi-year commitments are replacing the spot-market volatility that once defined these industries.
Cash Returns and a Cleaner Balance Sheet
Operating cash flow was $1.7 billion and free cash flow nearly $1.5 billion. Capital spending was $211 million, 5% of revenue, with a fiscal 2027 range of 4% to 6%. Seagate retired $1.2 billion of debt in the quarter and a further $750 million after quarter end, leaving principal debt of about $1.6 billion, and the chief financial officer expects the company to be net cash positive by the end of calendar 2026. It returned $568 million through dividends and buybacks, raised the quarterly dividend by about 3% to $0.76 per share, and has $4.4 billion of repurchase authorization left. Management said repurchases should increase significantly from calendar 2027.
Guidance Above the Quarter, Shares Below
For the December quarter Seagate guided to revenue of $4.8 billion, plus or minus $100 million, and adjusted EPS of $9.20, plus or minus $0.20. Non-GAAP operating expenses are expected near $300 million and operating margin is expected to move toward the mid-50% range, and the company said fiscal 2027 revenue growth should meaningfully exceed fiscal 2026. Two of the sources I reviewed, 24/7 Wall St. and a KuCoin report of Odaily’s coverage, differ on whether the guidance beat analysts’ estimates, and I could not compare it to a consensus figure myself.
The stock fell after hours despite the report. KuCoin, citing MSX.COM data, put the decline at more than 8%. I treat that figure with caution, as it comes from a single secondary source, but the direction is consistent across the reports I reviewed. When a stock has rallied into a report, a clean beat and a higher forecast can be treated as the expected outcome rather than as news.
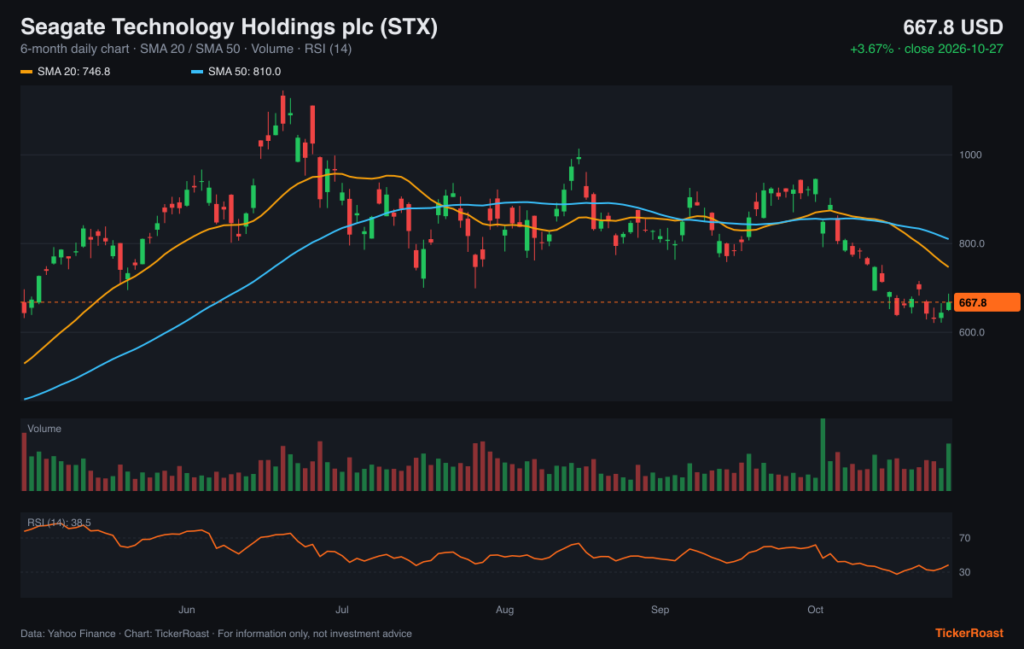
The chart shows the shares against their 20-, 50- and 200-day moving averages, with the relative strength index below. The first thing to check is how far the stock stood above those averages going into the report, because a stretched reading is the usual setting for a sell-the-news reaction. That describes positioning, not a forecast. The next datapoint is the December-quarter report, where Seagate will need to deliver the roughly $9.20 of earnings it has just put on the table.
Note: Seagate’s own press release could not be opened when this article was prepared, so the financial figures come from the earnings call summary and the secondary reports cited above.
Sources
- Seagate Technology Q1 Earnings Call Highlights — Yahoo Finance
- Seagate Tops Q1 2027 Estimates but Guides to $4.8B Next Quarter — 24/7 Wall St.
- Seagate Q1 Revenue Exceeds Expectations, Shares Decline After Hours — KuCoin
- Seagate Technology Reports Fiscal First Quarter 2027 Financial Results — Seagate
Market data: Yahoo Finance, close of 2026-10-27. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 28, 2026 and market data as of the 2026-10-27 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

