

October 27, 2026 | TickerRoast Markets Analysis
Royal Caribbean reported third-quarter results on October 27, 2026 that came in above its own guidance, and it lifted its full-year earnings range. The detail I find most telling, though, sits further down the release: bookings for 2027 sailings are up in the high teens, at higher prices than a year ago.
A Record Summer, With Costs Pushed Into the Fourth Quarter
According to the earnings release filed with the SEC, revenue rose 9% to $5.6 billion and net income reached $1.7 billion, or $6.45 per share. Adjusted EPS came to $6.57, up from $5.75 a year earlier. The company carried 2.7 million guests, 9% more than last year, on capacity up 8%, with ships sailing at a 112% load factor, meaning more than two guests per cabin on average.
Pricing was less spectacular than the headline numbers suggest. Net yields, the industry’s measure of revenue per available berth day, rose only 0.6% in constant currency, helped by late bookings in Europe and the Caribbean. Net cruise costs excluding fuel fell 1.8% per available berth day, but the company says that partly reflects expenses that shifted into the fourth quarter. In other words, part of this quarter’s beat is timing, and I would not extrapolate it.
| Metric | Q3 2026 | Q3 2025 |
|---|---|---|
| Revenue | $5.6B | +9% y/y |
| Adjusted EPS | $6.57 | $5.75 |
| Net yields (constant currency) | +0.6% | — |
| Guests carried | 2.7M | +9% y/y |
| Load factor | 112% | — |
The Guidance Raise and What Holds It Back
Royal Caribbean now expects adjusted EPS of $17.85 to $17.95 for 2026, with full-year net yields up about 2.1% in constant currency. For the fourth quarter alone, it guides to adjusted EPS of $3.48 to $3.58 and much stronger net yield growth of 4.2% to 4.7%. The company says the raise reflects the stronger third quarter, partly offset by higher fuel costs and currency.
Fuel is the variable I watch most closely for cruise operators right now. Royal Caribbean expects fuel expense of $379 million in the fourth quarter and $1.345 billion for the year, and it has hedged 58% of 2026 consumption and 53% of 2027. Its guidance uses current pump prices rather than a forecast, and it estimates that a 10% move in fuel prices changes costs by about $15 million over the rest of the year. With oil prices elevated this autumn, the unhedged portion matters.
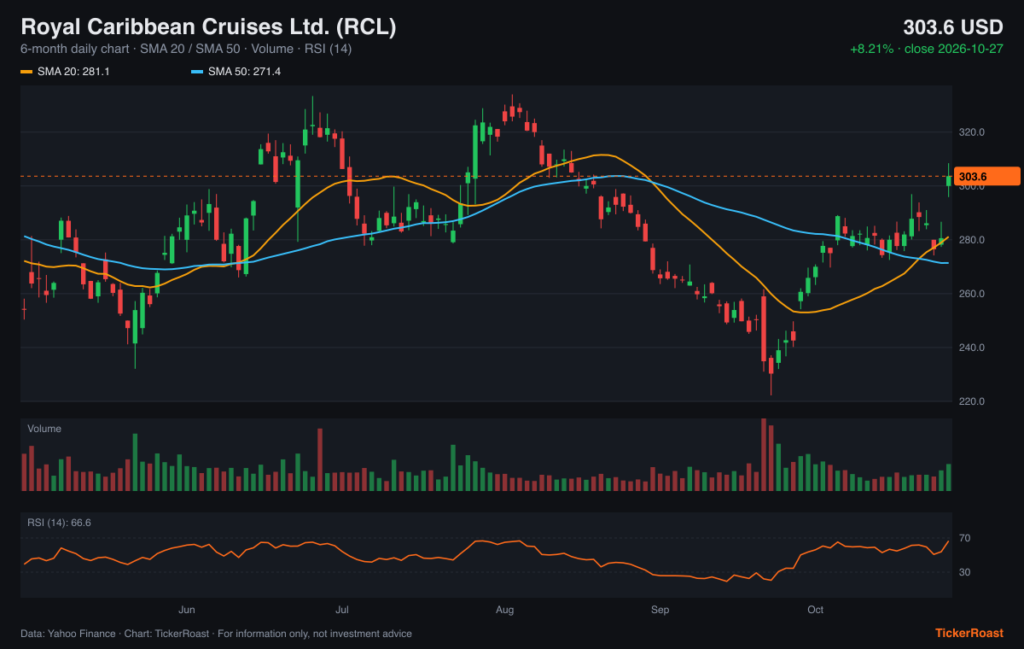
2027 Is Where the Story Is Heading
CEO Jason Liberty said that “2027 bookings are pacing ahead of historical levels at higher rates,” adding that it is still early in the booking cycle. Booking volumes since the last earnings call are up in the mid-teens across major channels. That matters because the company’s Perfecta program targets 20% annual adjusted EPS growth from 2024 through 2027, which it describes as a $20-handle EPS in 2027. Liberty also said the company is “already above” its target of a 17% return on invested capital.
The balance sheet supports that ambition but does not leave unlimited room. Liquidity stood at $7.4 billion at the end of September, against $2.2 billion of debt due within a year and $20.1 billion of long-term debt. Over nine months, the company spent $1.04 billion on buybacks and paid $1.08 billion in dividends, while 2026 capital spending is expected at about $4.6 billion, mostly ships and private destinations. The pending purchase of a 50% stake in Sandals and Beaches resorts, expected to close in early 2027, adds a land-based leg to the strategy that investors will want to see priced and financed in detail.
Sources
- Royal Caribbean Group third quarter 2026 earnings release (Form 8-K, Exhibit 99.1) — Royal Caribbean Group / SEC
Market data: Yahoo Finance, close of 2026-10-27. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 27, 2026 and market data as of the 2026-10-27 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

