

October 28, 2026 | TickerRoast Markets Analysis
Robinhood reported the highest quarterly revenue in its history on Tuesday evening, and shares still fell about 8% in after-hours trading. The reason sits in the mix: options and equities boomed while crypto and interest income shrank.
A Record Top Line With a Weaker Bottom Line
According to the company’s third-quarter 2026 earnings release, Robinhood generated net revenues of $1.42 billion, up 12% from a year earlier. Net income was $476 million, down 14%, and diluted earnings per share were $0.51, down 16%. On an adjusted basis EPS was $0.60, 3% lower. Chief Financial Officer Shiv Verma described the period as the company’s “highest quarter ever for revenues.” Both statements are true, and the gap between them is the story.
Total operating expenses rose 16% to $739 million, faster than revenue. Adjusted EBITDA still grew 9% to $808 million, a 57% margin, so the business remains very profitable. But with costs growing faster than sales and two large revenue lines moving the wrong way, earnings per share could not keep up.
Options and Equities Are Doing the Heavy Lifting
| Revenue line | Q3 2026 | Change vs. a year earlier |
|---|---|---|
| Options | $399 million | +31% |
| Equities | $121 million | +41% |
| Crypto | $120 million | -55% |
| Total transaction-based | $867 million | +19% |
| Net interest | $415 million | -9% |
Transaction-based revenue rose 19% to $867 million, and options alone contributed $399 million. Equities revenue of $121 million was up 41%. Together with crypto, those three lines account for $640 million of the $867 million; the remaining roughly $227 million, my arithmetic from the release, comes from other transaction categories. Crypto, at $120 million, is now about 14% of transaction revenue, down from roughly a third of the total a year ago, again by my arithmetic. That is what a 55% decline in a single line does to a mix.
Net interest revenue is the second drag. At $415 million it fell 9% year over year and now represents roughly 29% of net revenue, again by my calculation. The release does not break out the cause, but net interest income at a brokerage typically depends on interest rates and the cash and margin balances customers hold, so it is worth watching how it behaves as the Fed approaches a decision on rates.
The Customer Numbers Keep Climbing
The user metrics argue that the franchise itself is healthy. Funded customers reached 28.7 million, up 7%. Total platform assets rose 19% to $396 billion. Robinhood Gold subscribers grew 34% to 5.2 million, which matters because subscriptions are less volatile than trading. Net deposits were $15.7 billion in the quarter, according to the release text, and $71.0 billion over the trailing twelve months.
Gold growth of 34% is the figure I would put next to the crypto decline. A subscriber base expanding that quickly gives the company a recurring revenue stream that does not depend on crypto trading volumes, though the release does not say how much Gold contributes to the total.
Guidance: A Small Cut to Costs, Not a Bold Reset
For 2026, Robinhood lowered the top end of its adjusted operating expenses and stock-based compensation outlook by $25 million, to a range of $2.675 billion to $2.75 billion from $2.675 billion to $2.775 billion. The guidance excludes provisions for credit losses, costs tied to pending acquisitions and potential significant regulatory matters. It is a modest tightening, and it implies the company is not planning to spend its way out of the crypto slowdown.
How the Shares Are Positioned
The stock fell about 8% after hours on the results, according to TipRanks, which attributed the move to weak crypto offsetting strength elsewhere. Google searches for “hood stock” were also among the faster-rising business queries in the United States over the last 24 hours.
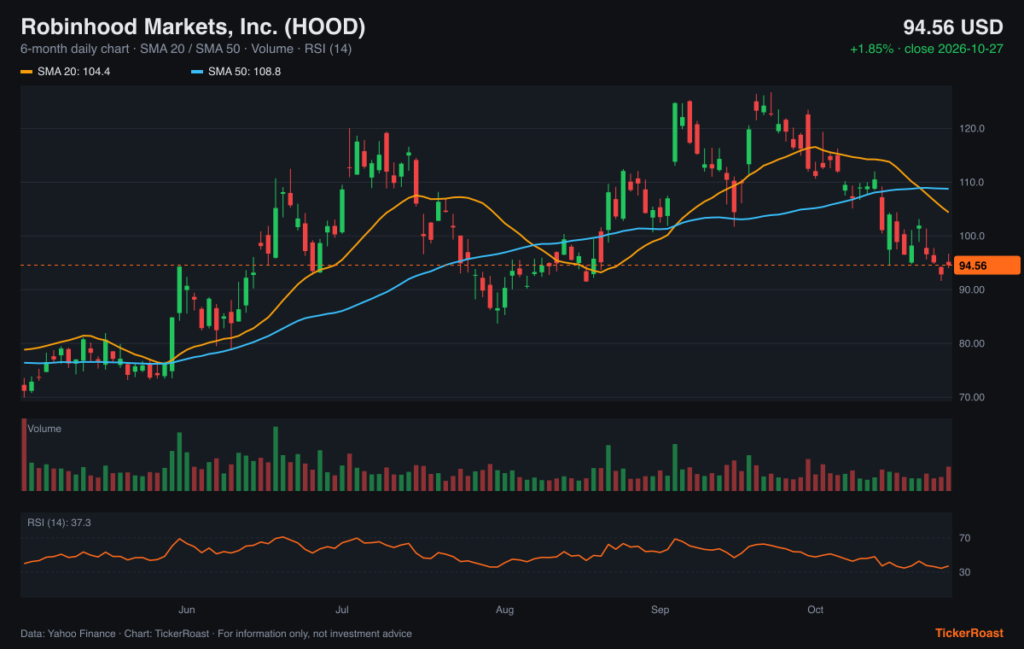
The chart shows the price relative to its 20-, 50- and 200-day moving averages, with volume and the 14-day relative strength index below. An after-hours drop of this size makes the first regular session the real test of how much of the earnings reaction holds.
What I will be watching next is whether options volumes stay elevated if equity markets cool, and whether the 55% crypto decline stabilizes. The next quarterly report will show whether a record revenue quarter was a plateau or a waypoint.
Sources
- Robinhood Markets, Inc. Reports Third Quarter 2026 Results (Exhibit 99.1) — SEC / Robinhood
- Futures Trade Mixed Ahead of Big Tech Earnings and the Fed’s Rate Decision — TipRanks
Market data: Yahoo Finance, close of 2026-10-27. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 28, 2026 and market data as of the 2026-10-27 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

