
November 3, 2026 | TickerRoast Markets Analysis
Election Day opens with a split tape. Apple’s soft margin forecast is dragging Dow futures lower while chipmakers lead a rebound in Nasdaq contracts, Asia’s tech-heavy markets fell more than 3.5% overnight, and oil is holding near $105 a barrel. Voters decide control of Congress today, AMD reports after the close, and the October jobs report lands on Friday.
The Rotation Out of Tech Continued on Monday
Monday extended the pattern of the last week. According to CNBC, the Nasdaq Composite fell 1.07% and the S&P 500 lost 0.51% as investors kept rotating out of technology stocks, while the Dow Jones Industrial Average rose about 214 points, or 0.41%. A blue-chip index finishing higher while the Nasdaq loses more than 1% is exactly what a rotation looks like: money is not leaving equities, it is leaving the crowded AI trade for cheaper, more defensive names.
That context matters for how I read this morning’s futures. The selling in megacap technology has now lasted long enough that each new earnings report is judged less on the quarter just ended than on what it implies for margins and spending in 2027.
Apple and Palantir Slide After Hours
Two of the most widely held technology stocks reported after Monday’s close, and both are lower this morning. Apple beat on revenue and earnings per share, but its guidance for a 45% to 46% gross margin in the December quarter came in below the 46.3% analysts expected, according to CNBC, which reported the stock about 4% lower in premarket trading. Apple’s own release shows September-quarter revenue of $114.5 billion, up 12%, and a reported gross margin of 47.9% that includes about one point from tariff refunds. I look at what the margin guide means in a separate analysis this morning.
Palantir is the other casualty. Its third-quarter release shows revenue up 96% to $2.313 billion, the first quarter above $2 billion in the company’s history, and U.S. commercial revenue overtaking U.S. government revenue for the first time. CNBC’s list of premarket movers nonetheless had the shares down nearly 8%. The sticking point, as I explain in my Palantir piece, is a sharp slowdown in new contract bookings.
Chipmakers Lead a Bounce in Nasdaq Futures
The futures board is unusual this morning. CNBC reports that Dow futures were 359 points lower, or 0.7%, with Apple’s weight in the price-weighted average doing most of the damage, while S&P 500 futures slipped 0.1% and Nasdaq-100 futures climbed 0.4%. The support came from semiconductors: Micron rose almost 4%, AMD and Intel gained more than 3% each, and Broadcom and Nvidia were up around 2%, according to the same CNBC live blog. After last week’s crash in chip stocks, that is a tentative return of buyers rather than a change of trend.
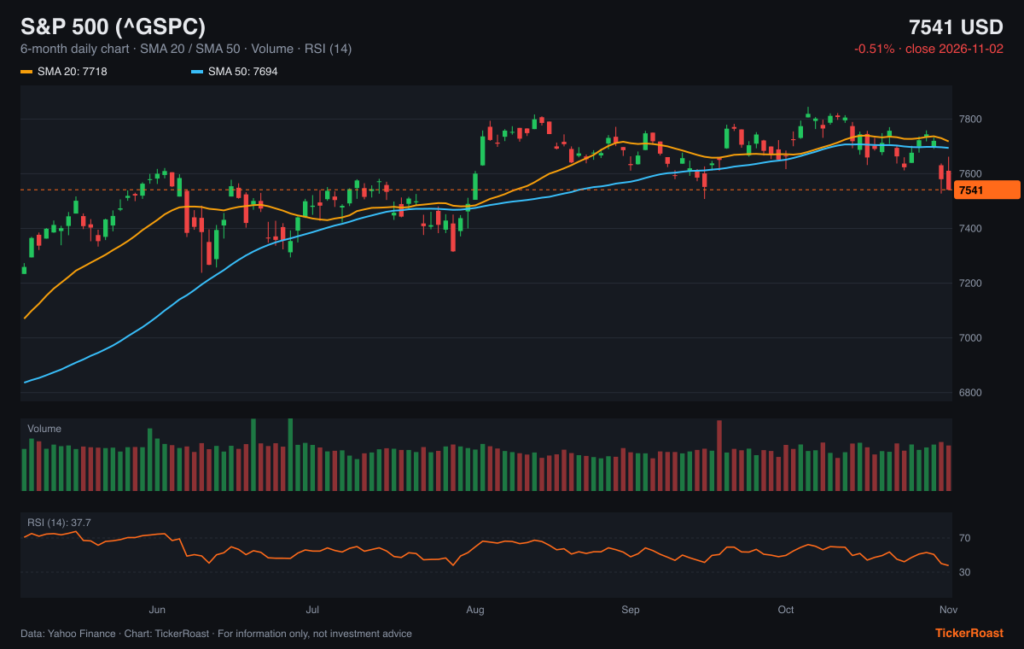
The chart shows the S&P 500 over the past six months with its moving averages, volume and RSI. Monday’s 0.51% decline left the index at 7,541, below both its 20-day average near 7,718 and its 50-day average near 7,694, after months in which those averages acted as support. The RSI has slipped to about 38, weak but not yet oversold, and the index now sits roughly 300 points below its October highs above 7,800. Yahoo Finance’s futures panel put S&P 500 contracts at about 7,564 before the open, so the index starts the day with little cushion above its late-October lows.
Seoul and Taipei Lead Asia Lower
Asia did not share the U.S. chip rebound. CNBC reports that South Korea’s Kospi fell 3.59% to 5,648.79 and the small-cap Kosdaq lost 4.08%, while Taiwan’s weighted index also fell 3.59%, to 43,307.54. Mainland China’s CSI 300 slipped 0.2%. Australia’s S&P/ASX 200 was the exception with a 0.34% gain, even though the Reserve Bank of Australia raised its cash rate by 25 basis points to 4.85%, its highest level since November 2008 and its fifth increase this year, according to CNBC.
Europe opened lower as well. CNBC reports that ASML fell 3.4%, STMicroelectronics and Infineon 3.9% each, and ASM International 2.1% in early trading. There were bright spots: Bayer jumped as much as 5.6% after raising its full-year guidance on the back of its pharmaceutical business, and Drax rose 8.2% in London after announcing a data center partnership with Brookfield, a project I cover in a separate article. On the other side, auto parts maker Schaeffler said it would cut 3,460 jobs and close five sites in Europe.
Oil Near $105 and a 10-Year Yield Above 4.9%
Energy remains the market’s background stress. According to CNBC, Brent crude was marginally higher at around $105 a barrel and West Texas Intermediate advanced nearly 1% to around $97 as tensions in the Middle East simmered. The 10-year Treasury yield rose about one basis point to 4.91%, the 30-year was at 5.28% and the 2-year held at 4.59%. With crude this high and long-term yields near 5%, the market has little room for an inflation surprise.
In crypto, Binance co-founder Changpeng Zhao told Yahoo Finance that withdrawals have been restored and that users did not suffer any loss after last week’s roughly $6.3 billion hack. Yahoo’s market panel showed bitcoin near $77,200 this morning.
Pfizer Beats Before the Bell, JOLTS Follows
The morning calendar is busy. Pfizer reported adjusted earnings of $0.87 per share on revenue of $16.6 billion and raised its full-year revenue guidance by $1.5 billion at the midpoint, according to its release; CNBC had the shares flat in premarket trading. Yum Brands beat with adjusted earnings of $1.56 per share, while Zebra Technologies fell more than 6% despite a beat, as its free cash flow guidance came in marginally below estimates, according to CNBC. Revvity gained 7% after raising its earnings forecast.
On the macro side, Yahoo Finance notes that the Labor Department releases its Job Openings and Labor Turnover Survey today. After last week’s hot inflation data, a firm labor market would make it harder for the Federal Reserve to resume cutting.
The Midterms and AMD Arrive After the Close
The two biggest events of the day come after the bell. AMD reports this evening, and as Yahoo Finance points out, Intel’s collapse last week showed that the reaction will depend as much on fourth-quarter guidance as on the quarter itself. Then come the election results. Yahoo Finance reports that prediction markets put the odds of Democrats taking the Senate at 73.1%, below the 80.3% implied by two polling-based models. CNBC notes that a Democratic sweep of both chambers could weigh on the market on Wednesday, especially on AI stocks, because investors have not firmly positioned for it.
The week then builds toward Friday, when the Bureau of Labor Statistics publishes the October employment report at 8:30 a.m. Eastern, according to its release schedule. Between an election, an AI bellwether and a payrolls report, this is a week in which the market’s recent nervousness will be tested from three directions at once.
Sources
- Dow futures drop 300 points on Election Day as Apple declines, oil rises: Live updates — CNBC
- Stocks making the biggest moves premarket: Pfizer, Apple, Palantir, Zebra Technologies & more — CNBC
- Apple Q4 2026 earnings live updates — CNBC
- Stock market today: Dow, S&P 500, Nasdaq futures waver ahead of midterm election results, AMD earnings — Yahoo Finance
- Apple reports fourth quarter results (Exhibit 99.1) — Apple / SEC
- Palantir Q3 2026 results (Exhibit 99.1) — Palantir / SEC
- Pfizer Reports Third-Quarter 2026 Results (Exhibit 99) — Pfizer / SEC
- Schedule of Releases for the Employment Situation — Bureau of Labor Statistics
Market data: Yahoo Finance, close of 2026-11-02. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of November 3, 2026 and market data as of the 2026-11-02 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
 Nasdaq Futures Sink on Amazon and Intel as Binance Loses $6.3 Billion: Your Friday Morning Brief
 Nasdaq Futures Slide on Alphabet, GDP and PCE at 8:30 and Amazon After the Bell: Your Thursday Morning Brief
 Oil Near $115, a Fed Decision at 2 p.m. and Microsoft and Alphabet After the Bell: Your Wednesday Morning Brief
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.