

October 29, 2026 | TickerRoast Markets Analysis
On the night Alphabet fell about 10% after hours, Microsoft went the other way. Azure growth accelerated to 48%, revenue beat expectations and management guided to even faster cloud growth. The price is a capital spending bill that doubled from a year ago and pushed free cash flow lower.
Azure Accelerates Again
Microsoft’s earnings release for the first quarter of fiscal 2027, the three months to Sept. 30, shows revenue up 19% to $92.3 billion and operating income up 21% to $45.9 billion. GAAP net income rose 32% to $36.6 billion, or $4.92 per diluted share. Excluding the impact of its investments in OpenAI, non-GAAP earnings per share were $4.89, up 18%. According to SiliconANGLE, analysts expected $4.73 per share on revenue of $90.69 billion.
Azure revenue grew 48%, and the 10-Q filing adds that it rose by $10.8 billion year over year, driven by demand across all workloads. SiliconANGLE reports Azure revenue of $33.17 billion against an expected $32.32 billion. In its July release, under the old reporting definition, Microsoft had reported 43% growth for Azure and other cloud services, so the definitions are not identical, but the direction is clearly up. Microsoft Cloud revenue rose 30% to $63.9 billion, and commercial remaining performance obligation, the contracted backlog, jumped 73% to $677 billion.
A New Map of the Business
This was the first quarter under Microsoft’s new reporting structure. The company now has two segments: Agents and Infra, which combines applications and agents, its multi-model system and Azure, and Devices and Consumer. Agents and Infra revenue rose 25% to $76.8 billion, while Devices and Consumer slipped 3% to $15.5 billion. Inside the consumer segment, Windows OEM and devices revenue fell 22% and Xbox content and services fell 2%, while search and advertising revenue excluding traffic acquisition costs rose 12%.
| Metric | Q1 FY2027 | Year-over-year change |
|---|---|---|
| Revenue | $92.3B | +19% |
| Operating income | $45.9B | +21% |
| Agents and Infra revenue | $76.8B | +25% |
| Devices and Consumer revenue | $15.5B | -3% |
| Microsoft Cloud revenue | $63.9B | +30% |
| Azure revenue growth | 48% | +$10.8B y/y |
| Commercial RPO | $677B | +73% |
| Additions to property and equipment | $39.4B | vs $19.4B |
The Bill for Capacity
The cash flow statement is where the cost of this growth shows up. Additions to property and equipment rose to $39.37 billion from $19.39 billion a year earlier, roughly double. Cash from operations increased to $58.0 billion from $45.1 billion, which leaves about $18.6 billion of free cash flow by my calculation, down about 27% from roughly $25.7 billion a year ago. Including finance leases, SiliconANGLE reports total capital expenditure of $45.2 billion.
Management is not slowing down. SiliconANGLE reports that Microsoft expects capital spending above $50 billion in the second quarter, and chief financial officer Amy Hood said demand still exceeds supply. The 10-Q also warns that power availability and grid connection delays could restrict the company’s ability to expand data center capacity. Cash, cash equivalents and short-term investments fell to $64.5 billion from $76.8 billion at the end of June, and the Microsoft Cloud gross margin slipped to 66% on a shift in mix toward Azure.
I think this is the crucial difference with Alphabet’s reaction. Both companies are spending heavily, but Microsoft is showing faster growth on the line that capital spending is supposed to feed. As long as Azure accelerates, investors seem willing to accept the cash flow drag.
Guidance Points Higher
For the second quarter, Microsoft guided revenue to $96.0 billion to $97.1 billion and Azure growth of 49% to 50% in constant currency, according to SiliconANGLE, which cites analyst expectations of $95.6 billion in revenue and 45.1% Azure growth. That is a rare combination for a company of this size: a beat, an acceleration and a higher bar for the next quarter all at once.
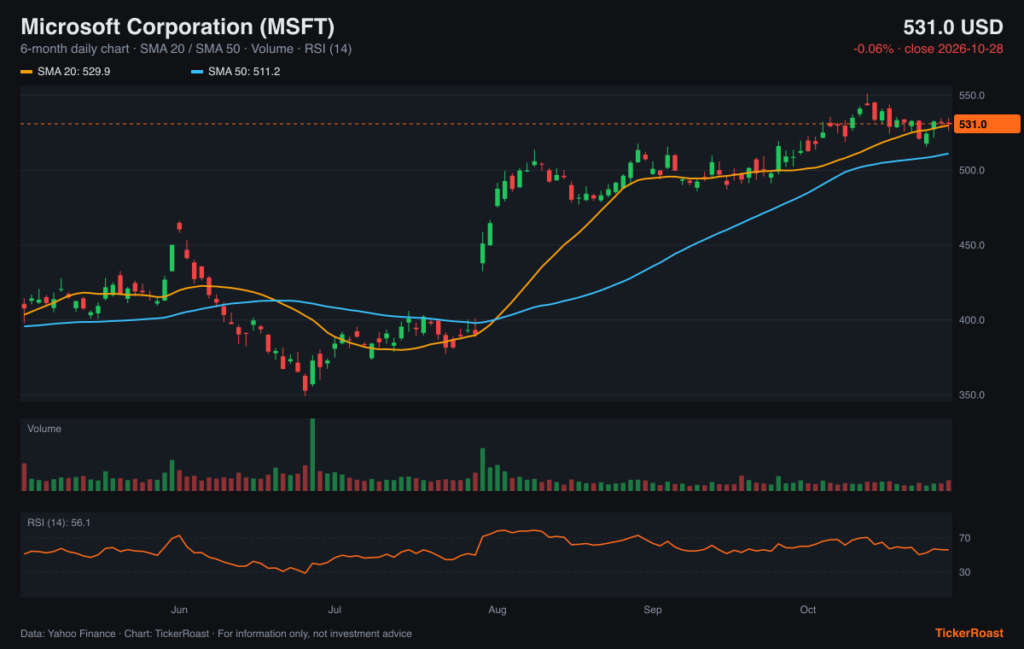
The chart above shows Microsoft’s six-month price action through Wednesday’s regular-session close, before the after-hours move. According to Stock Titan, the shares were up 4.9% at 6:02 p.m. Eastern, while the AP reported a gain of nearly 3% in later extended trading, so the size of the move this morning remains to be confirmed at the open. Going into the report, the stock had been consolidating near $531, just above its 20-day average of about $530 and well above its 50-day average of about $511, with an RSI of 56. A gain of 3% to 5% would push it toward the October high near $550.
Copilot and the Workforce
Microsoft 365 commercial cloud revenue rose 17%, or 18% in constant currency, and the 10-Q attributes the growth to higher revenue per user from premium offerings including Microsoft 365 Copilot, E5 and E7, along with usage of GitHub Copilot. SiliconANGLE reports that Hood said the E7 bundle has reached millions of seats, though Microsoft did not update its paid Copilot seat count this quarter. In July, Satya Nadella said Microsoft 365 Copilot had passed 30 million paid seats.
The company is also getting leaner. The 10-Q says total headcount decreased 2% from a year ago, and operating expenses rose only 6% despite heavy investment in research compute. That came a day after reports that Microsoft offered voluntary exits to thousands of employees, which TickerRoast covered on Tuesday. Microsoft returned $10.2 billion to shareholders through dividends and buybacks in the quarter.
The question I will be watching is whether the backlog converts as quickly as the capacity comes online. A $677 billion commercial RPO gives Microsoft extraordinary visibility, but it also depends on delivering data center capacity in a market where power, components and leases are all constrained. For now, the numbers suggest Microsoft’s spending is translating into revenue faster than its peers’.
Sources
- Microsoft Announces First Quarter Results (Exhibit 99.1) — Microsoft (SEC filing)
- Microsoft Form 10-Q for the quarter ended September 30, 2026 — Microsoft (SEC filing)
- Microsoft Announces Fourth Quarter Results (July 2026) — Microsoft (SEC filing)
- Microsoft’s stock rises on solid earnings and revenue beat, with Azure growing 48% — SiliconANGLE
- Stock Market Today Live October 28, 2026 — Stock Titan
- Asian shares and U.S. futures are mixed after Alphabet’s earnings disappoint — Associated Press via AOL
Market data: Yahoo Finance, close of 2026-10-28. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 29, 2026 and market data as of the 2026-10-28 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

