

October 27, 2026 | TickerRoast Markets Analysis
Coca-Cola delivered the kind of quarter consumer staples investors look for: 5% volume growth, a wider margin and a higher full-year target. What caught my attention, though, is where that growth came from. North America, the company’s most profitable market, sold exactly the same number of cases as a year ago.
A Clean Beat on Both Lines
According to the results filed with the SEC on October 27, 2026, net revenue rose 7% to $13.4 billion and organic revenue also grew 7%. Comparable EPS increased 11% to $0.91, while reported EPS reached $0.93. Yahoo Finance cited consensus estimates of $0.88 per share and about $12.9 billion of revenue, so the company beat on both.
One detail tempers the revenue figure. Concentrate sales, which is what Coca-Cola actually invoices to its bottlers, grew 7%, two points ahead of unit case volume because of shipment timing. Part of this quarter’s revenue was effectively pulled forward, and management’s own guidance mentions slight destocking in the fourth quarter.
| Region | Unit case volume growth |
|---|---|
| Latin America | +6% |
| Asia Pacific | +6% |
| Europe, Middle East & Africa | +5% |
| North America | Flat |
| Bottling Investments | +8% |
Zero Sugar Keeps Doing the Heavy Lifting
By brand, trademark Coca-Cola grew 5%, Coca-Cola Zero Sugar jumped 16% and Diet Coke/Coca-Cola Light rose 6%. Water grew 8%, while sports drinks declined 3%. Price/mix contributed only 1 point of growth, which tells me this quarter was driven by volume rather than by price increases. After two years in which beverage makers leaned heavily on pricing, I see that as a healthier mix, but it also leaves less room if volumes soften.
Margins and a Higher Bar for 2026
The comparable operating margin widened to 32.9% from 31.9%. Currency helped: it added 2 points to EPS growth and 1 point to revenue. The company now expects comparable EPS growth of at least 11% for 2026, up from 9% to 10%, and at least 9% on a currency-neutral basis excluding acquisitions and divestitures, up from 7% to 8%. Free cash flow guidance moves to at least $13.0 billion from about $12.4 billion. Organic revenue growth is now expected to be at least 5%, essentially the same as before.
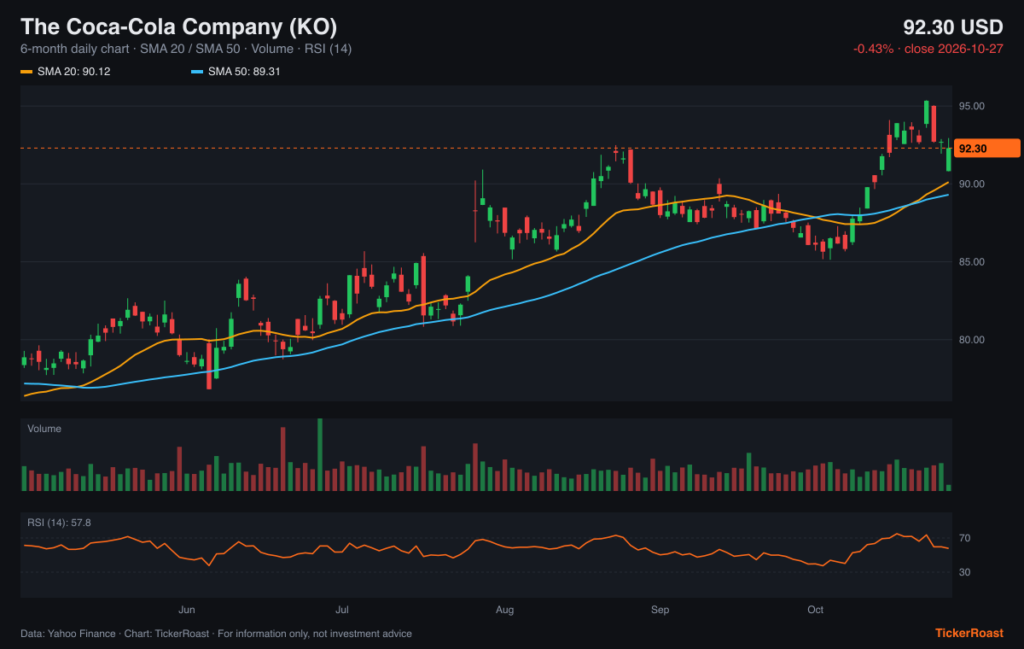
CEO Henrique Braun said the results “demonstrate our system’s sustained momentum.” The numbers support that, but the flat North American volume is the figure I would keep an eye on. It is the market where Coca-Cola earns the highest price per case, and a stall there, as CNBC also highlighted, was enough to keep the shares from rallying on the beat.
What Changes in the Fourth Quarter
The fourth quarter will look noisier. The outlook assumes the pending sale of the company’s African bottling operations closes during the quarter, and Coca-Cola expects acquisitions and divestitures to cut comparable net revenue by about 4%, partly offset by a 1% currency tailwind. The quarter also has six fewer days than last year. Taken together, I expect reported growth to slow sharply in the next report, even if underlying demand holds up, and the first 2027 guidance in February will show how much of this year’s momentum management believes it can carry forward.
Sources
- Coca-Cola Reports Third Quarter 2026 Results and Raises Full Year Guidance (Form 8-K, Exhibit 99.1) — The Coca-Cola Company / SEC
- Coca-Cola hikes earnings outlook, even as it sees lackluster demand in North America — CNBC
- Earnings live updates (Coca-Cola, Boeing, UPS) — Yahoo Finance
Market data: Yahoo Finance, close of 2026-10-27. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of October 27, 2026 and market data as of the 2026-10-27 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Any relevant financial interests held by the author or publisher in the securities mentioned are disclosed where applicable. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Anonymous reader poll, just for fun. Not investment advice.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.

