
November 5, 2026 | TickerRoast Markets Analysis
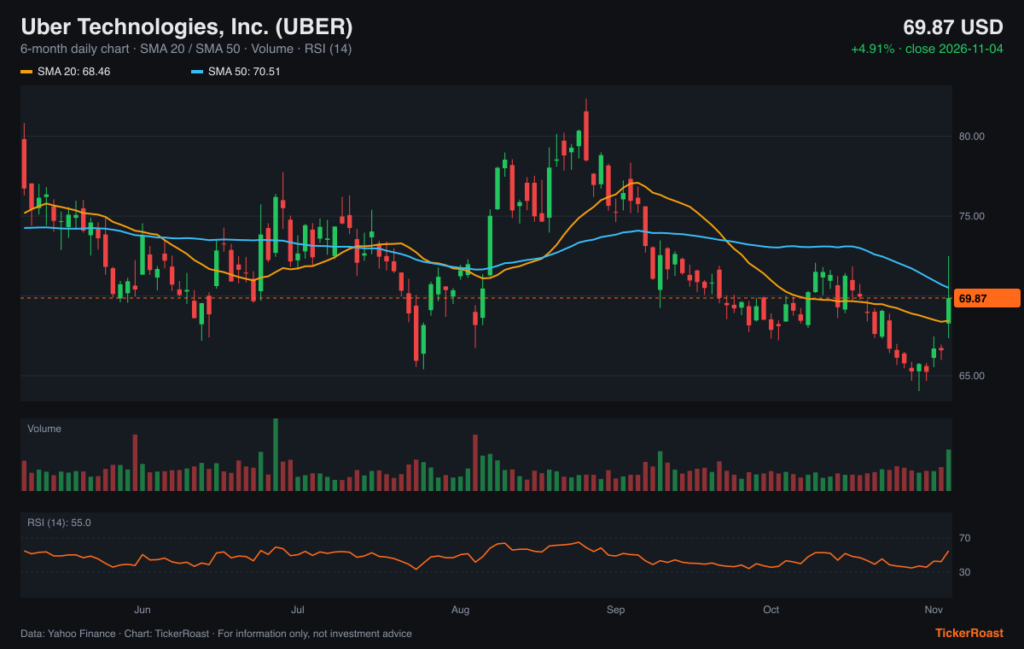
Uber Technologies shares closed Wednesday, Nov. 4, 2026, at $69.87, up about 4.9% from Tuesday’s close, based on Yahoo Finance data, after the company reported third-quarter gross bookings of $59.8 billion, up 20% from a year earlier. The gain came on a strong day for the whole market, and it came despite a fourth-quarter profit outlook that fell short of the analyst estimate compiled by LSEG, according to TheStreet. I think the two pieces together say a lot about what investors are now willing to pay for: volume first, and margins on trust.
A Fifth Straight Quarter Above 20%
The headline growth numbers were solid. Uber said trips grew 16% to 4.1 billion, monthly active platform consumers rose 14% to 215 million and trips per consumer rose 2%. Chief Executive Dara Khosrowshahi called it the company’s “fifth consecutive quarter of 20%+ Gross Bookings growth.”
Underneath, the mix is shifting. Mobility gross bookings rose 18% to $29.5 billion, Delivery climbed 22% to $28.5 billion and Freight jumped 35% to $1.77 billion. Delivery is now almost as large as rides by bookings, and it is growing faster.
Revenue is a different story. Total revenue rose only 10% to $14.8 billion, and Mobility revenue actually fell 2% to $7.52 billion. Uber said business model changes reduced total revenue growth by 8 percentage points. That gap between 20% bookings growth and 10% revenue growth is the first thing I would want explained on any model of the company, because it changes how much of each dollar of bookings Uber keeps on the top line.
Profitability Keeps Expanding
On the profit side, Uber posted GAAP income from operations of $1.45 billion, up 30%, and adjusted EBITDA of $2.96 billion, up 31%. Adjusted EBITDA reached 5.0% of gross bookings, up from 4.5% a year earlier, and non-GAAP operating income was a record 3.9% of bookings. Mobility segment operating income rose 27% to $2.36 billion, and Delivery rose 30% to $1.06 billion.
GAAP net income attributable to Uber was $512 million, or $0.25 a diluted share, down from $6.63 billion, or $3.11, a year earlier. I would not read much into that comparison: the company said the third quarter of 2025 included a $4.9 billion benefit from a tax valuation release and a $1.5 billion gain from revaluing equity investments, while this quarter included a $476 million pre-tax loss on those investments. Non-GAAP EPS rose 35% to $0.88.
Cash generation was healthy. Operating cash flow was $2.64 billion, free cash flow was $2.54 billion, and unrestricted cash, cash equivalents and short-term investments stood at $10.1 billion at quarter end.
The Outlook and the Driver Problem
For the fourth quarter, Uber guided to gross bookings of $63.25 billion to $65.25 billion, or 18% to 22% growth in constant currency, and non-GAAP EPS of $0.95 to $0.99, which it said translates to adjusted EBITDA of $3.13 billion to $3.23 billion. According to TheStreet, citing LSEG data, analysts had expected fourth-quarter adjusted EPS of $1.06.
TheStreet also reported that Uber cited a shortage of drivers, higher fuel costs and the Middle East conflict as factors weighing on ride-hailing growth in markets including India, Brazil and Canada. According to the same report, which quotes Reuters, Khosrowshahi told analysts the company is moving incentive spending from riders to drivers, a shift that could lead to higher fares.
This is the part of the report I find most important. A ride-hailing network depends on balancing supply and demand, and when supply gets scarce the company has to pay for it. If incentive dollars move from riders to drivers, Uber protects availability, but riders may see higher prices. With fuel costs elevated, the cost of keeping drivers on the road has risen at the same time.
Autonomy and a Leadership Change
Khosrowshahi said in the release that Uber’s focus on autonomous vehicles “is now on commercial execution,” with about 700 fully driverless vehicles expected on the platform by the end of the year and more than 2,000 in 2027. Those numbers are small next to 4.1 billion quarterly trips, but they are the first concrete fleet targets I have seen the company tie to a timeline.
Separately, Uber disclosed in an 8-K filing that Jill Hazelbaker, President and Chief Corporate Affairs Officer, will step down on Nov. 30, 2026, for an external opportunity. Khosrowshahi described her as “a deeply trusted advisor.” Her departure comes as the company works through regulatory questions on autonomy and labor in many markets, which is the terrain her role has covered.
How the Stock Is Positioned
Even after Wednesday’s gain, the stock is well below its highs. Based on Yahoo Finance data, Uber closed at $69.87, compared with a 52-week closing high of about $94.10 and a closing low of $65.25 reached on Oct. 30. The relative chart below shows how far the stock has lagged the S&P 500 over the past year.
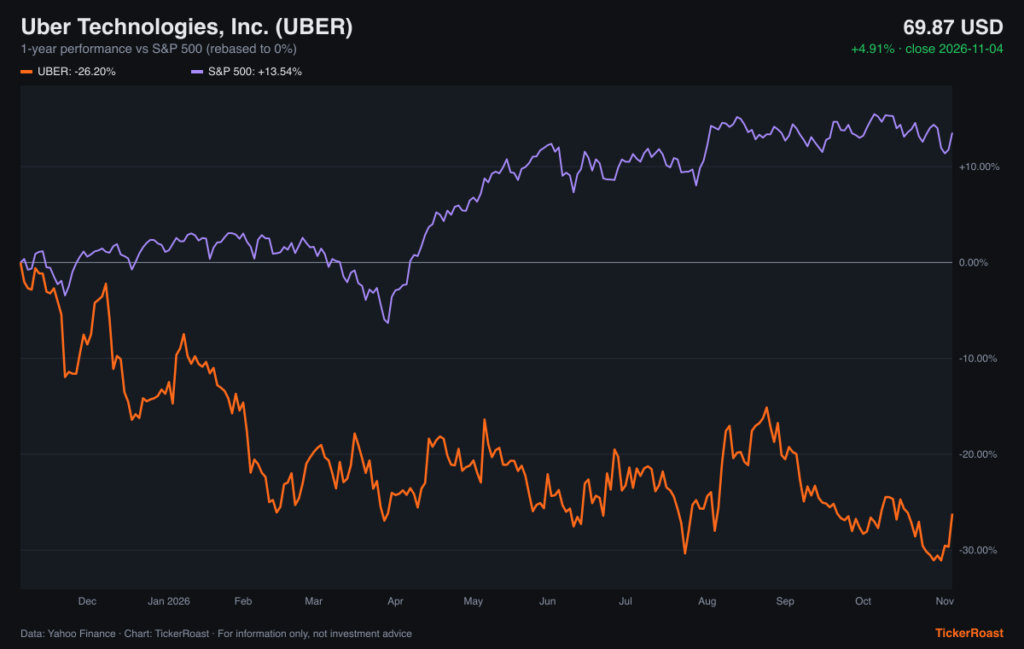
In my view, the quarter shows a business that keeps growing volume and margins at the same time, with the main open question being the cost of driver supply. Lyft is due to report after the close on Thursday, according to the Earnings Whispers calendar, and its commentary on drivers and pricing should help show whether the pressure Uber described is specific to its markets or industry-wide.
Sources
- Uber Announces Results for Third Quarter 2026 (Exhibit 99.1) — Uber / SEC EDGAR
- Uber Form 8-K, November 4, 2026 (Items 2.02 and 5.02) — SEC EDGAR
- Stock Market Today (Nov. 4, 2026): Uber shares climb after beating 3Q earnings forecasts — TheStreet
- Earnings calendar for Thursday, November 5, 2026 — Earnings Whispers
- UBER historical prices — Yahoo Finance
Market data: Yahoo Finance, close of 2026-11-04. Charts generated by TickerRoast from this data.
Disclaimer: This article is for informational and educational purposes only. It provides general financial and business analysis and does not constitute investment advice, a personal recommendation, a recommendation to buy, sell or hold any security, or an offer to transact in any financial instrument. Information is based on publicly available sources as of November 5, 2026 and market data as of the 2026-11-04 close (Yahoo Finance). Past performance is not a reliable indicator of future results; forecasts are uncertain and actual results may differ materially. Investing in shares involves risk, including the loss of capital. The publisher does not guarantee the accuracy or completeness of the information and accepts no responsibility for investment decisions made on the basis of this article. Readers should consult official company disclosures, conduct their own research and, where appropriate, seek advice from a licensed financial adviser. Conflicts of interest: At the time of writing, the author and TickerRoast have no position in the securities mentioned and receive no compensation from the companies discussed. This article was prepared with the assistance of AI tools and is based on the sources listed above.
Read next
Get the daily market briefing
The stories that move markets, in your inbox every trading day at 9 a.m. ET. Free, unsubscribe anytime.